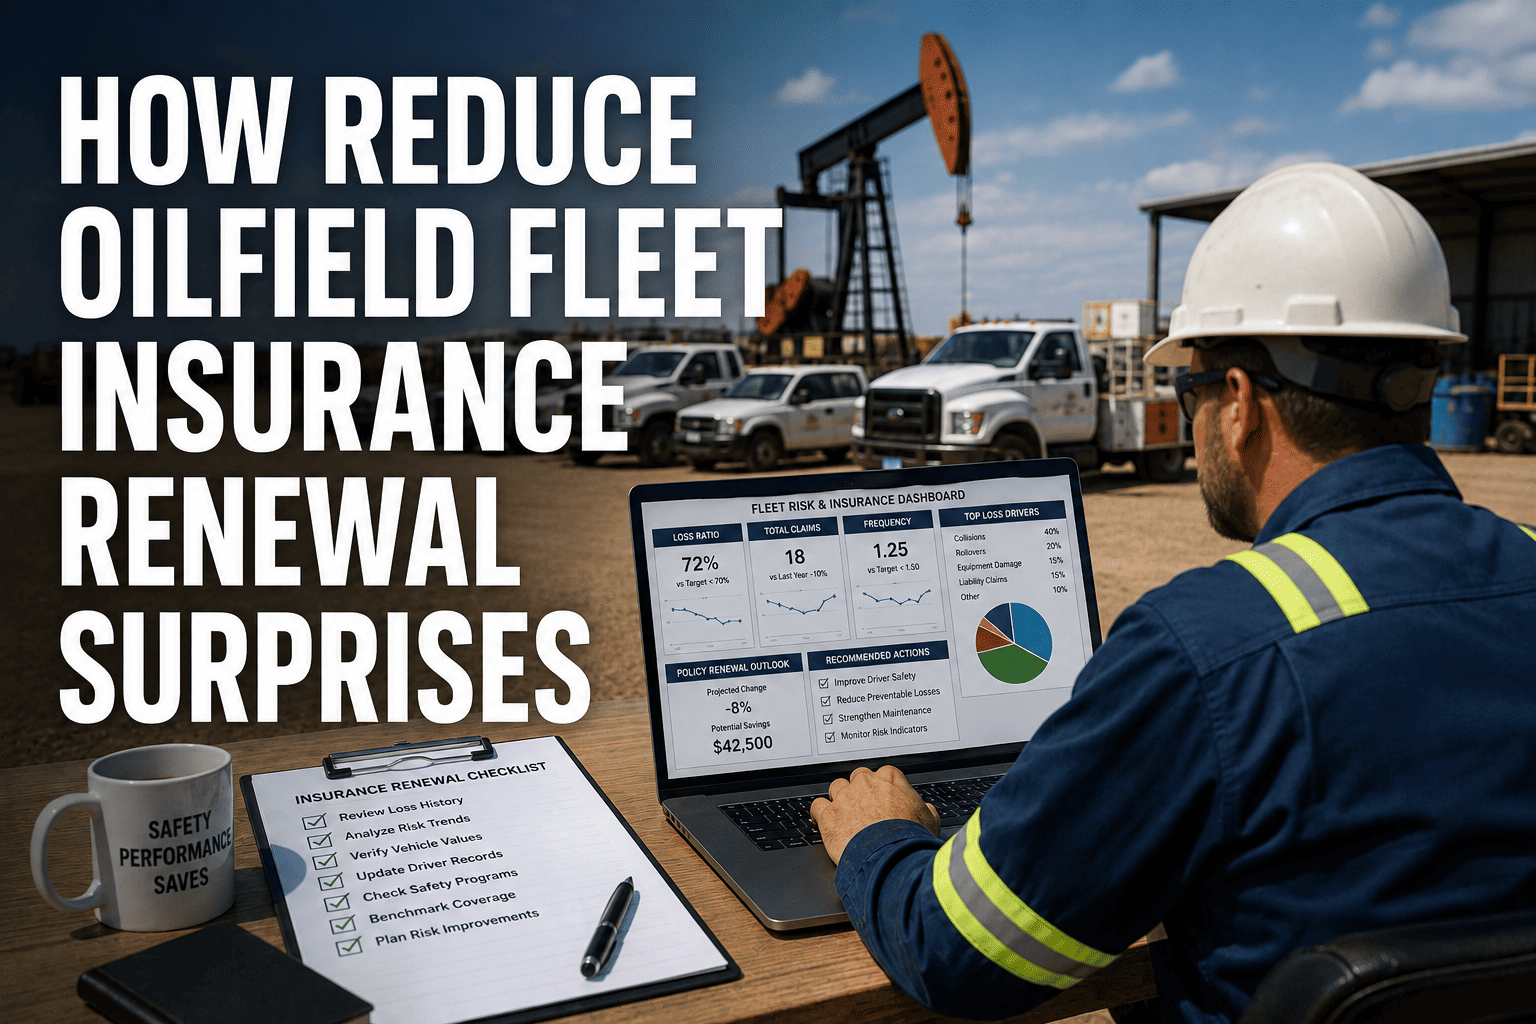
The email arrives sixty days before renewal and the number stops you mid-sip. Your oilfield fleet insurance premium is jumping 18 percent with no clear explanation beyond market conditions and loss ratio adjustments. Your safety manager insists the fleet had a good year. Your maintenance records show improved compliance. Your incident count was lower than the prior term. Yet the underwriter sees something different, and that something different is a fragmented data picture that fails to tell your actual fleet performance story. Oilfield fleet insurance renewals generate surprises not because carriers are unreasonable but because the data gap between what fleet managers know and what underwriters see is enormous. Closing that gap with structured year-round data collection turns renewal from a guessing game into a predictable business process.
Oilfield fleet insurance premiums have increased 15 to 35 percent at renewal for many operators over the past three years. The primary driver is not market hardening alone but poor data presentation that forces underwriters to default to industry-wide loss assumptions rather than fleet-specific performance. Operators who submit structured safety, maintenance, and incident data packages at renewal achieve 5 to 15 percent lower premiums than those who submit basic vehicle lists and loss runs.
Why Oilfield Fleet Renewals Generate Surprises
Insurance renewal surprises in oilfield fleets stem from a fundamental timing mismatch. Fleet managers think about insurance sixty days before renewal when the broker requests information. Underwriters evaluate fleet risk based on data that should have been collected continuously throughout the policy term. When the renewal data request arrives, fleet managers scramble to assemble twelve months of information from disconnected systems, paper files, and memory. The result is an incomplete picture that underwrites conservatively because they cannot verify positive fleet performance claims. An operator who reduced incidents by 30 percent but cannot produce trend data to prove it receives no credit for the improvement. A fleet that achieved 95 percent preventive maintenance compliance but lacks systematic records gets rated as if compliance is unknown. The surprise is not that premiums increase but that operators are surprised when they fail to document the improvements they actually achieved.
The oilfield operating environment amplifies this problem because the risk profile is inherently higher than general trucking. Off-road operations, remote locations, hazardous materials transport, heavy equipment movements, and harsh weather exposure all elevate base risk. Underwriters pricing oilfield fleets start from a higher baseline and look for specific evidence that the operator manages these elevated risks better than average. Without that evidence, the operator gets average-or-worse pricing in a high-risk category, which produces premium levels that feel surprising even when they are actuarially predictable. FleetRabbit solves this problem by collecting the data underwriters want continuously throughout the policy term so the renewal package writes itself from accumulated evidence. Sign up for FleetRabbit to start building your next renewal data package from day one.
What Underwriters Actually Evaluate Beyond Loss Runs
Loss runs show what happened but underwriters increasingly focus on what an operator does to prevent losses from happening. The shift from reactive to proactive underwriting means that two fleets with identical loss histories can receive dramatically different premiums based on their risk management infrastructure. Understanding what underwriters evaluate allows operators to build data collection systems that directly address pricing factors.
Driver Safety Performance and Management
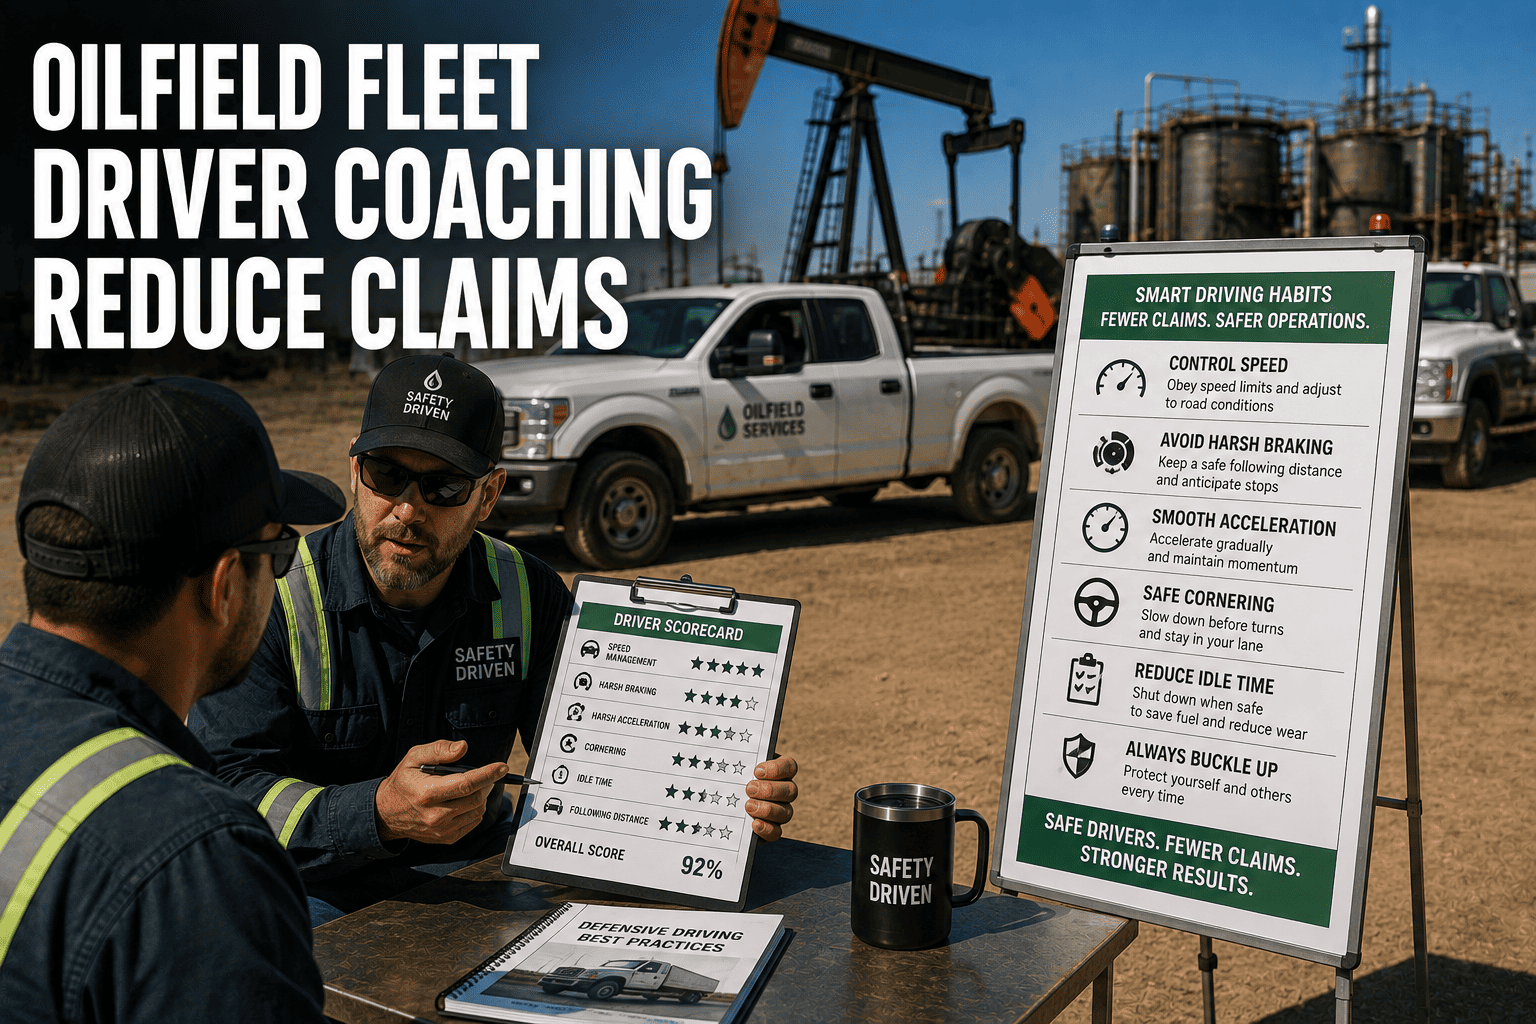
Underwriters evaluate whether an operator has systematic driver safety management or relies on reactive responses to incidents. They look for evidence of ongoing driver training programs with documented completion rates, driver scorecards based on telematics data showing speeding, harsh braking, and fatigue patterns, driver qualification file completeness including license verification and medical card tracking, and progressive discipline records showing that safety violations are addressed consistently. An operator who can demonstrate that 95 percent of drivers completed quarterly safety training, that average driver safety scores improved 15 percent over the policy term, and that all driver qualification files are current and complete presents a dramatically different risk picture than an operator who simply reports no major incidents. The absence of incidents without supporting management evidence does not convince underwriters that the absence is intentional rather than lucky.
Telematics Data as Underwriting Evidence
Telematics data has become the most influential non-loss factor in oilfield fleet underwriting over the past three years. Underwriters specifically want to see fleet-wide speeding event frequency trending down or stable, harsh braking and cornering event rates below industry benchmarks for oilfield operations, hours-of-service compliance rates with minimal violations, and idle time percentages that indicate efficient operations rather than extended unauthorized stops. The key is trend direction, not absolute numbers. A fleet that started the policy term with high speeding event rates but reduced them by 40 percent through coaching demonstrates active risk management. A fleet with low event rates that are trending upward raises underwriter concern about deteriorating discipline. FleetRabbit generates underwriter-ready telematics summaries that show exactly these trends in the format underwriters prefer.
Maintenance Compliance and Vehicle Condition
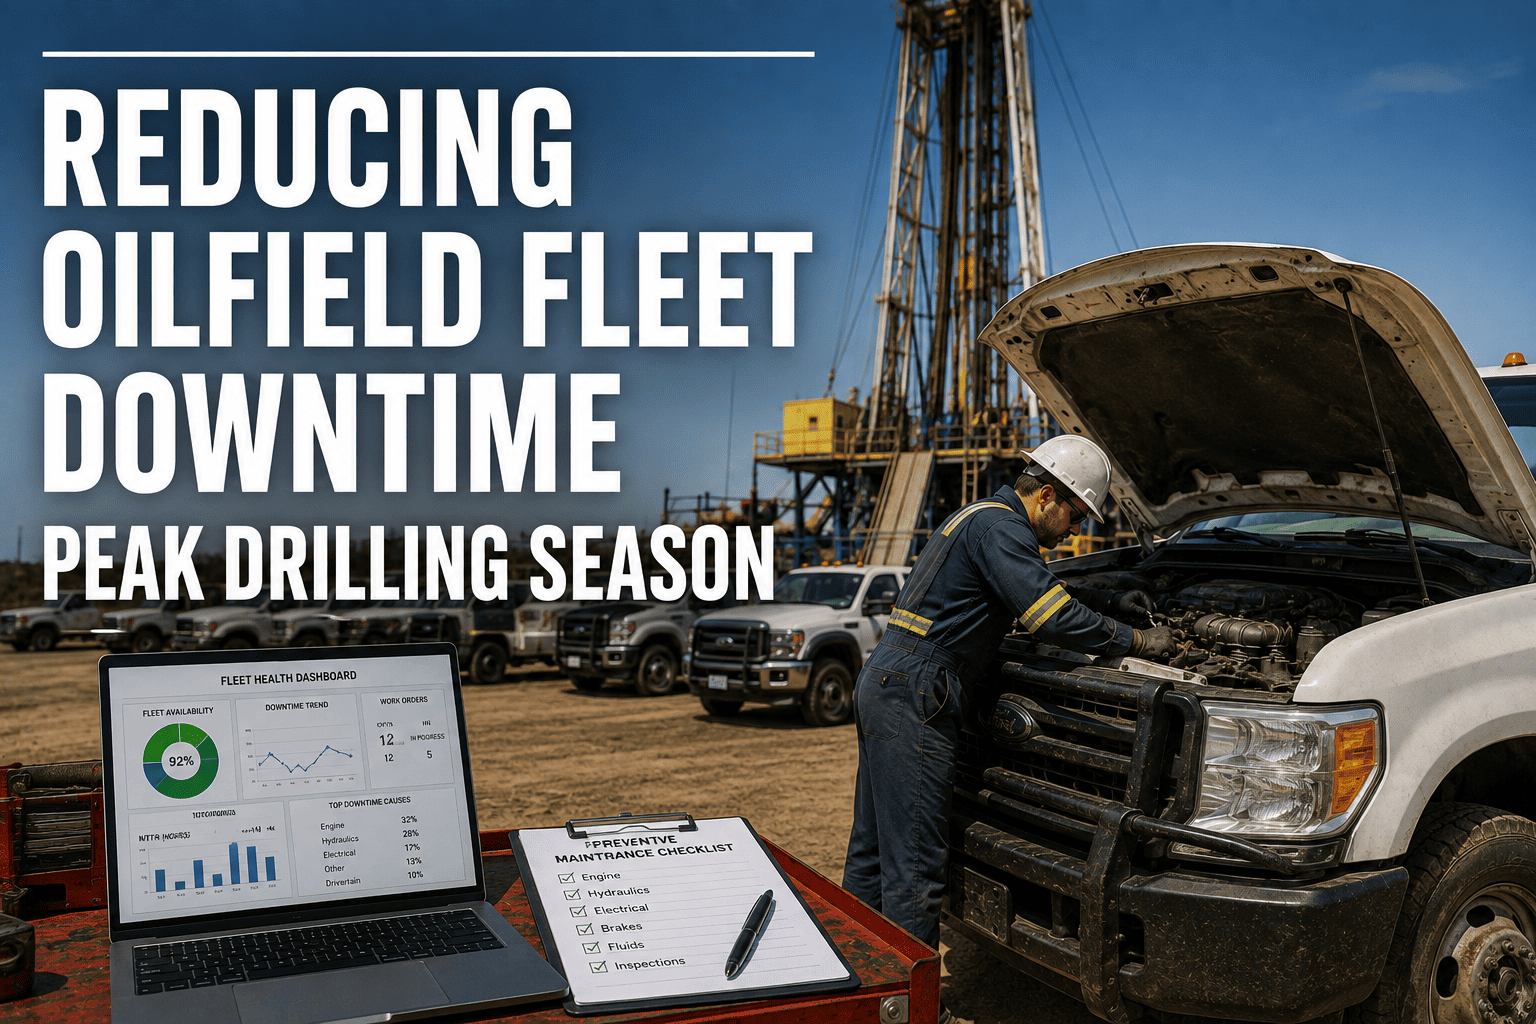
Vehicle condition directly affects both accident probability and severity, making maintenance data a core underwriting factor. Underwriters evaluate preventive maintenance completion rates as a percentage of scheduled services actually performed on time, the ratio of planned to unplanned maintenance indicating whether the fleet is proactive or reactive, average vehicle age and mileage relative to replacement policy, and specific high-risk system maintenance like brake inspections, tire condition tracking, and safety system functionality. A fleet with 92 percent preventive maintenance compliance, a 75 to 25 planned-to-unplanned maintenance ratio, and documented brake and tire inspection records presents as well-managed. A fleet where maintenance records are incomplete, where unplanned repairs exceed planned maintenance, or where vehicle ages exceed replacement policy raises concerns about deferred maintenance creating hidden risk. Book a demo to see how FleetRabbit generates maintenance compliance reports that underwriters respond to positively.
Incident Trend Analysis and Root Cause Response
How an operator responds to incidents matters as much as the incident count itself. Underwriters want to see incident trending over multiple policy periods showing improvement or stability, root cause analysis documentation for every reportable incident, corrective action implementation and verification records, and near-miss reporting programs that indicate proactive hazard identification. An operator with eight incidents in a policy term but detailed root cause analysis and documented corrective actions for each one presents better than an operator with five incidents and no documented response. The five-incident operator looks like they are not learning from their experiences, while the eight-incident operator looks like they are actively managing risk even when incidents occur. This counterintuitive dynamic means that better documentation of incident response can actually improve pricing even when incident counts are not ideal.
FleetRabbit collects driver safety scores, maintenance compliance rates, incident trends, telematics summaries, and risk exposure data continuously. When renewal arrives, your underwriting package is already assembled with twelve months of verified data. No scramble, no gaps, no conservative pricing from missing information.
The Year-Round Data Collection Framework
Eliminating renewal surprises requires shifting from a sixty-day renewal preparation window to a continuous twelve-month data collection cycle. The framework has four phases that run concurrently throughout the policy term, each feeding a specific section of the eventual underwriting package.
| Data Category | Collection Method | Frequency | Underwriting Impact |
|---|---|---|---|
| Driver Safety Scores | Telematics-based scoring on speeding, braking, cornering, and fatigue indicators | Continuous with monthly summaries | High impact, directly influences driver risk rating factor |
| Maintenance Compliance | Automated tracking of scheduled services versus completed services with documented verification | Per-event with monthly compliance rate calculation | High impact, affects vehicle condition risk assumption |
| Incident Records | Digital incident reporting with root cause analysis, corrective actions, and verification | Per-incident with quarterly trend analysis | Critical impact, loss runs plus response quality drive base pricing |
| Training Completion | Learning management system integration with automated completion tracking per driver | Per-training event with quarterly completion rate reports | Moderate impact, demonstrates management commitment to safety |
| DOT Compliance | Automated hours-of-service monitoring, inspection compliance, and violation tracking | Continuous with monthly violation summaries | High impact for DOT-regulated operations, violations directly affect eligibility |
| Risk Exposure Metrics | Miles driven by road type, off-road operation hours, hazardous materials miles, and geographic risk zones | Continuous with quarterly exposure summaries | Moderate impact, validates that exposure assumptions match actual operations |
Assembling the Underwriting Package That Gets Results
The data collection framework produces raw material that must be assembled into a structured underwriting package that tells your fleet performance story clearly and convincingly. The format matters as much as the content because underwriters review hundreds of submissions and respond best to clear, concise presentations that highlight key metrics without burying them in detail.
The Executive Summary Page
The first page of your underwriting package must communicate your fleet's risk profile in under sixty seconds. Include fleet size and composition with vehicle types and average ages, total miles and hours operated during the policy term, incident count with year-over-year trend comparison, preventive maintenance compliance rate with trend, average driver safety score with improvement trend, and a single-sentence summary of the most significant risk management improvement achieved during the term. This executive summary frames everything that follows and gives the underwriter a positive first impression before they dive into supporting detail. Operators who lead with a strong executive summary consistently receive better initial pricing than those who submit raw data without narrative context.
Supporting Data Sections
Each data category from the collection framework becomes a dedicated section with a consistent structure. Start with the headline metric and its trend direction, then provide the supporting data in chart format, then include a brief narrative explaining what actions drove the results. For example, the driver safety section would lead with average fleet safety score improved from 72 to 84 over the policy term, followed by a bar chart showing monthly average scores, followed by a narrative explaining that the improvement was driven by implementing monthly driver coaching sessions based on telematics alerts that reduced speeding events by 38 percent. This metric-chart-narrative structure allows underwriters to quickly grasp the performance story and verify the claims with the underlying data. FleetRabbit generates these sections automatically from the continuous data it collects, producing a complete underwriting package with a single export at renewal time.
Addressing Negative Trends Directly
The most damaging approach to negative trends is ignoring them. Underwriters will find negative data in loss runs and DOT inspection records regardless of whether you highlight them. An operator who proactively identifies a negative trend, explains the root cause, and documents the corrective action receives significantly better treatment than one who appears to be hiding problems. If your incident count increased in the third quarter due to a specific contract with unusual routing challenges, say so. Explain that the contract terms were renegotiated to eliminate the problematic routing and that fourth-quarter incidents returned to baseline levels. This transparency builds underwriter confidence that you understand your risk profile and manage it actively rather than hoping problems go unnoticed. FleetRabbit's trend analysis automatically flags negative trends early in the policy term, giving you months to implement corrections before renewal rather than discovering the problem when the underwriter points it out.
Third-Party Validation and Certifications
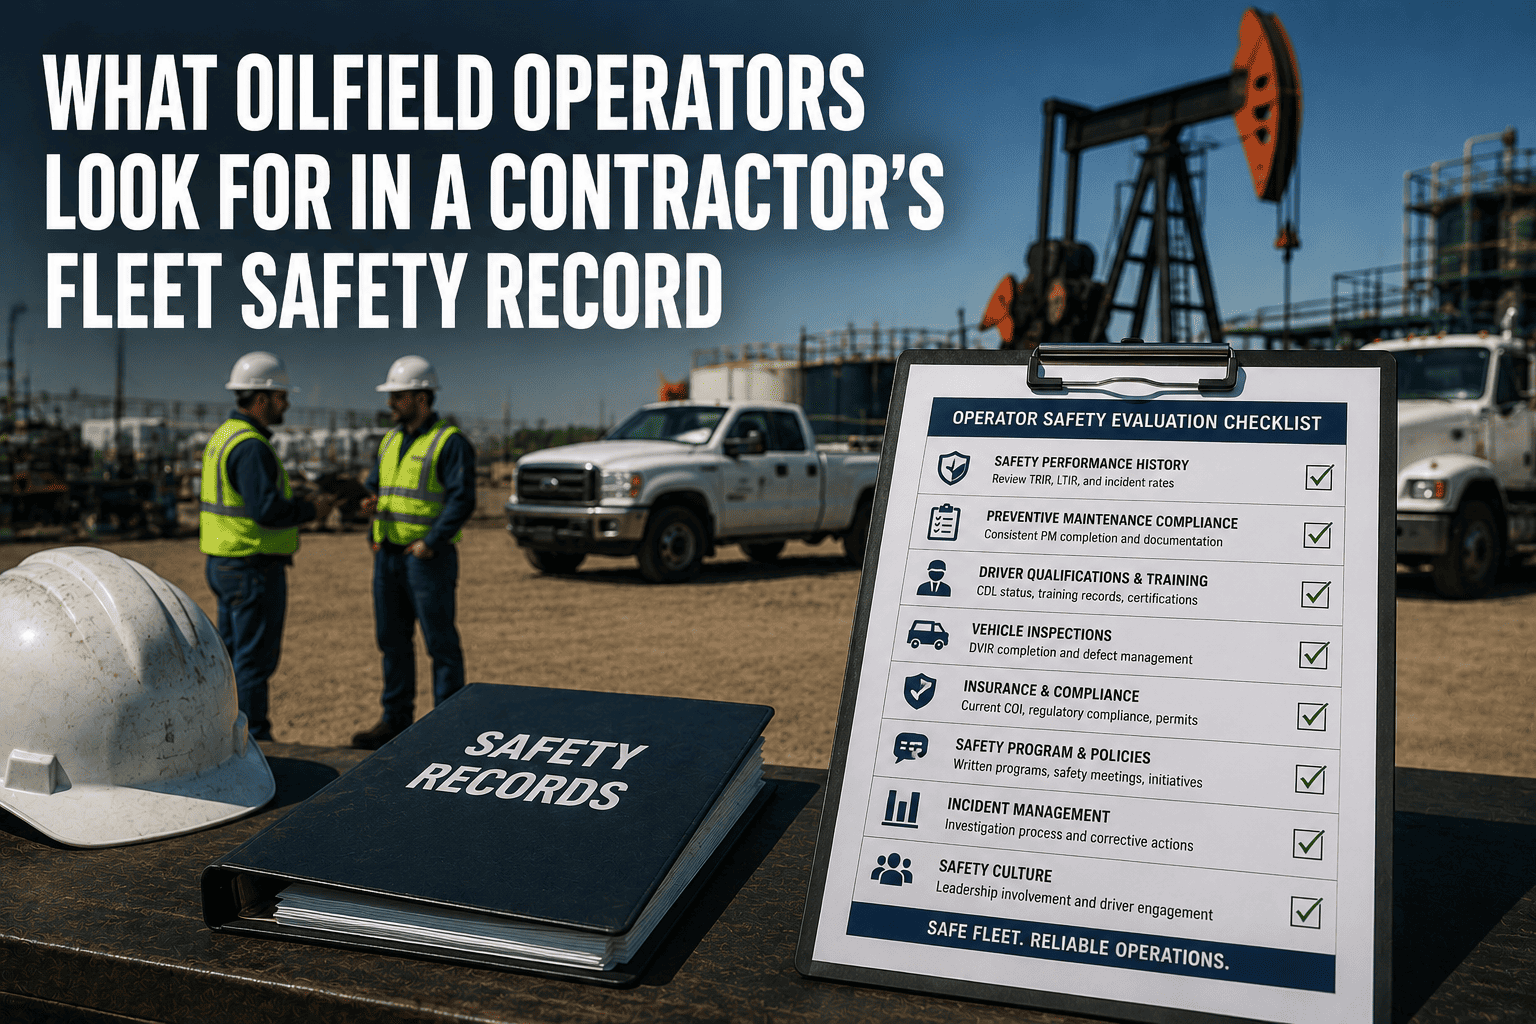
Include any third-party validations that independently verify your risk management quality. ISNetworld compliance scores, DOT safety measurement system scores with trend analysis, SafeLand or other industry safety certifications, and third-party audit results all provide underwriter confidence that your self-reported data is accurate. An operator with a strong ISNetworld score and improving SMS scores receives more credit for their data than an operator with equivalent data but no third-party verification. If you have achieved any industry safety awards or recognitions during the policy term, include them prominently because they signal to underwriters that your safety program is recognized as effective by industry peers, not just self-assessed.
FleetRabbit collects every data point underwriters need throughout the policy term and generates a complete underwriting package with executive summary, trend charts, supporting data, and narrative explanations with a single click. Your broker receives a professional package that demonstrates fleet quality and supports premium negotiation from a position of strength.
Common Mistakes That Trigger Renewal Surprises
Waiting Until Renewal to Start Collecting Data
This is the single most common and most expensive mistake. Data collected in the final sixty days before renewal only covers two months of a twelve-month policy term. Underwriters evaluating a fleet with two months of data must assume the other ten months were average or worse, which defeats the purpose of data submission entirely. The data collection system must be operating from day one of the policy term, not day 305. Operators who start collecting data mid-term can still benefit by showing improvement trends from the collection start date, but they cannot demonstrate full-term performance and receive proportionally less underwriting credit.
Submitting Raw Data Without Analysis
Handing an underwriter a spreadsheet with twelve months of telematics events or maintenance records without analysis creates more work for the underwriter and does not communicate your performance story. Underwriters are not going to analyze your raw data to find positive trends. They will look at the overall numbers, apply their standard assumptions, and move on. The analysis must be done by the operator and presented as conclusions supported by data, not as data waiting to be analyzed. FleetRabbit's automated package generation ensures that every data submission includes the analysis that turns raw numbers into compelling underwriting evidence.
Inconsistent Data Across Submission Categories
An underwriter who receives driver safety data showing zero violations but DOT inspection records showing four violations has identified an inconsistency that destroys credibility across the entire submission. Inconsistencies between data sources suggest that the operator is cherry-picking favorable data rather than presenting a complete picture. When inconsistencies exist, address them directly with explanations. If driver safety data shows zero speeding events but DOT inspections found speeding violations, explain that the telematics system was not fully deployed until mid-term and that the violations occurred before deployment. Honest explanation of data gaps is always better than apparent inconsistency that looks like data manipulation.
Negotiating Without Alternative Market Options
Even the best underwriting package loses leverage if the broker approaches a single carrier. The oilfield fleet insurance market has enough capacity that operators should always have two to three carrier options at renewal. A strong data package gives your broker the ammunition to create competitive tension between carriers, which is the most effective premium negotiation tool available. When carrier A sees that carrier B is reviewing the same strong submission, pricing discipline improves. Without competitive alternatives, even excellent data may not prevent a carrier from applying generic market increases. Building carrier relationships throughout the policy term, not just at renewal, ensures that multiple markets understand your fleet and can respond quickly with competitive pricing when renewal approaches. Sign up for FleetRabbit to build the data package that gives your broker competitive leverage at every renewal.
Every day you operate without structured data collection is a day of underwriting evidence that is lost forever. The safety improvements, maintenance compliance, and driver coaching you are doing right now will not count at renewal unless you are capturing the data to prove it. FleetRabbit starts collecting insurance-ready data from day one and generates a complete underwriting package when renewal arrives. Stop hoping for a good renewal and start building the evidence that guarantees one.