Renewal season used to mean opening an email and absorbing whatever increase landed in it. Oilfield fleets running lease roads, wellpad traffic, and long highway hauls have watched premiums climb year after year, often with no major claim to explain the jump. What's changed is that underwriters now have a way to price a fleet on its own actual behavior instead of an industry average, if the fleet can produce the data. This guide walks through the telematics evidence insurers actually weigh, how to turn raw sensor data into a renewal-ready case, and what a realistic premium reduction looks like. If you want to see what your own fleet's data could do at renewal, sign up for FleetRabbit or book a demo and we'll walk through it together.
Fleet insurance premiums have climbed 8 to 20 percent annually in recent years, even for fleets without major claims, and some oilfield operators saw increases pushing toward 30 percent in 2026. Roughly 60 percent of insurers now use telematics somewhere in underwriting, and fleets that document their safety performance with real driver and vehicle data typically see 15 to 30 percent premium reductions at renewal. Collecting the data isn't enough on its own, the fleets earning the biggest discounts are the ones actively coaching drivers on it within days, not months.
Why Insurers Are Asking For Your Data Now
Underwriting has traditionally leaned on fleet size, industry classification, and historical loss runs, numbers that describe where a fleet has been, not how it operates today. Telematics changes that by giving underwriters granular signals on routes, mileage, time of day, and driving behavior, which lets them price risk against what a fleet is actually doing rather than what similar fleets did last year. For an oilfield operator, that distinction matters more than most, because lease road conditions and wellpad traffic patterns don't map cleanly onto standard highway risk models.
The gap works against well-managed fleets more than anyone. A fleet that has tightened maintenance and coached out harsh-braking habits over the past year gets none of the credit for that improvement unless the data actually reaches the underwriter, which is why the fleets winning at renewal are the ones treating their telematics data as a negotiation asset instead of an internal dashboard nobody exports.
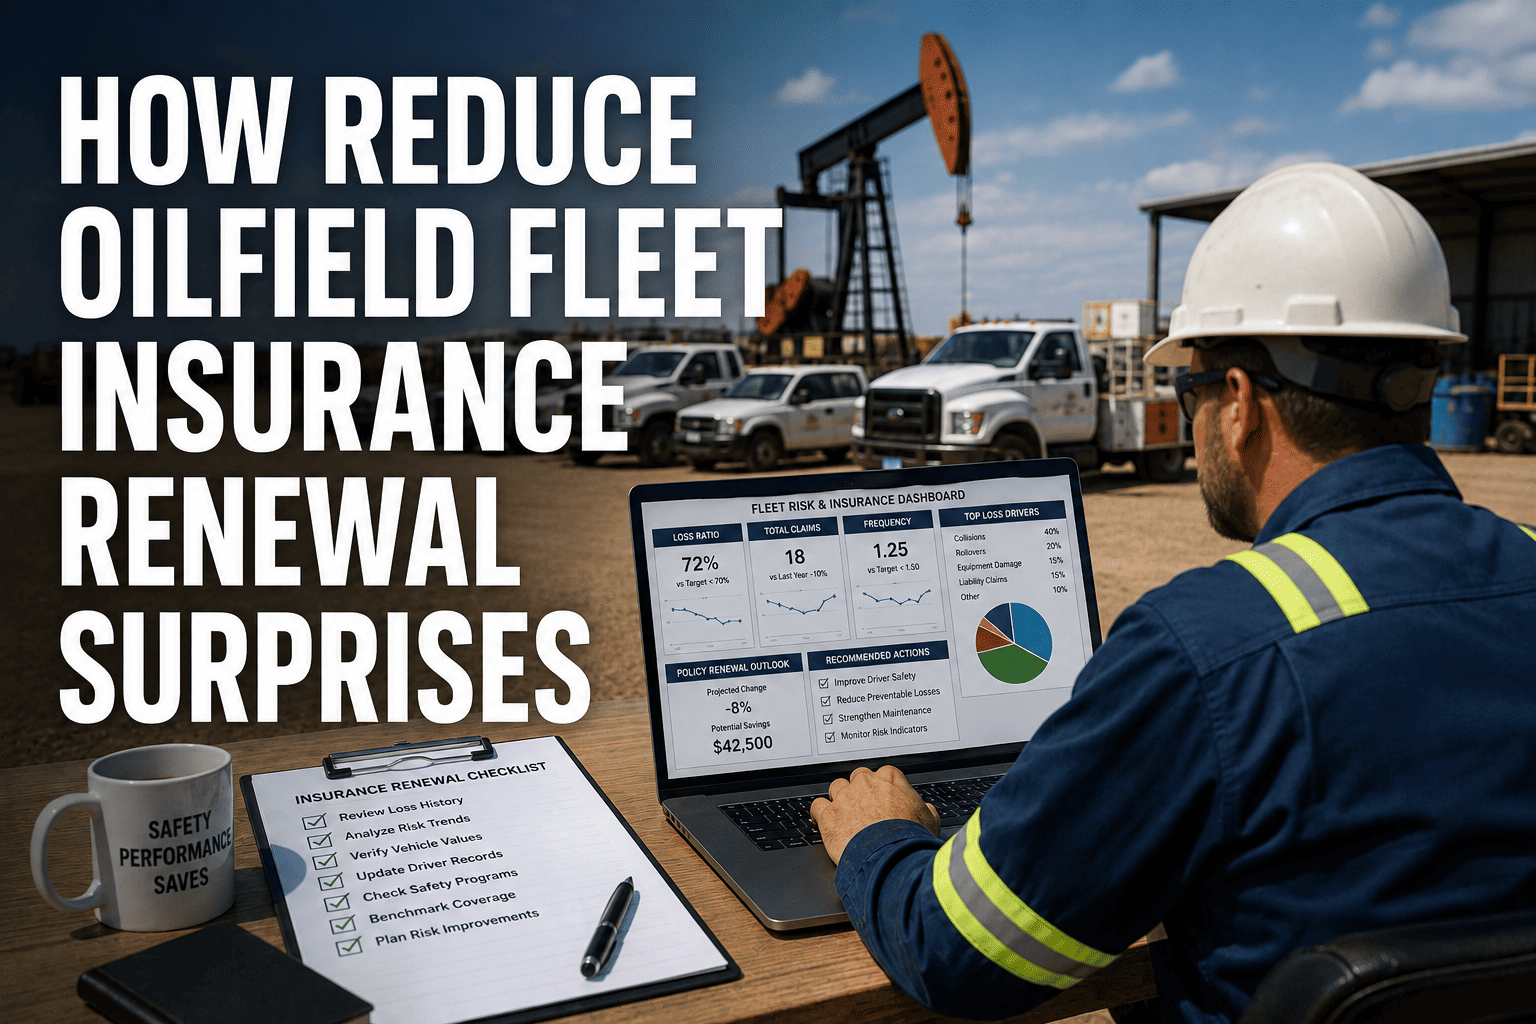
FleetRabbit tracks the exact signals carriers reward, harsh braking, speeding, HOS compliance, and inspection history, and packages them into a report your broker can bring straight into the renewal conversation.
The Five Metrics Insurers Weight Most
Not every data point moves the needle equally. Underwriters have told carriers what actually predicts claims, and it's a shorter list than most fleets expect.
| Metric | What It Signals | Why Underwriters Weight It |
|---|---|---|
| Harsh Braking Events | Frequency of hard-braking incidents per driver per month | Repeated hard braking correlates statistically with rear-end collision risk |
| Speeding Patterns | Time spent over posted limits, especially on lease roads and highway transitions | Speed is one of the strongest single predictors of claim severity |
| Distraction Alerts | Phone use and attention alerts pulled from in-cab camera systems | Distraction evidence demonstrates a genuine safety culture, not just a policy on paper |
| Hours of Service Compliance | Logged hours cross-checked against actual dispatch and drive time | Fatigue-related violations correlate with claim severity, not just frequency |
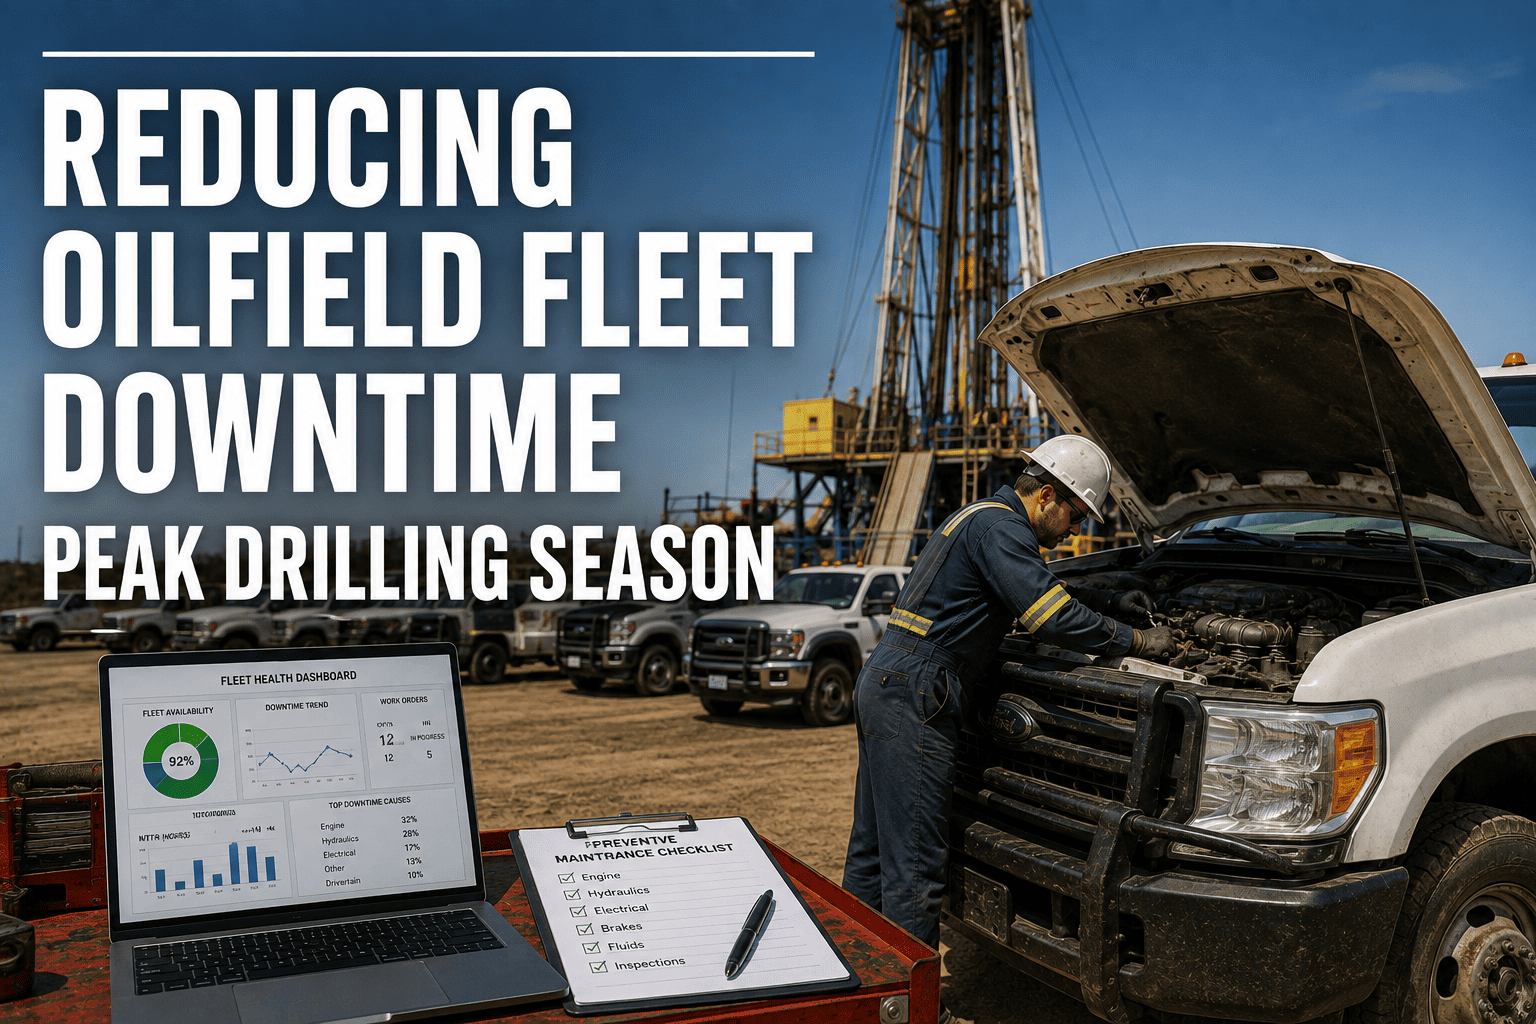
| Inspection and Maintenance History | Documented service records tied to each asset over time | Structured maintenance logs demonstrate reliability and reduce liability exposure |
Turning Raw Data Into a Renewal Discount
Fleets that consistently earn better pricing follow roughly the same process each renewal cycle.
Step One: Clean and Centralize the Data
Harsh-braking events, speeding logs, HOS records, and maintenance history need to live in one place, not scattered across a telematics dashboard, a spreadsheet, and a filing cabinet.
Step Two: Coach the Trend, Not Just the Event
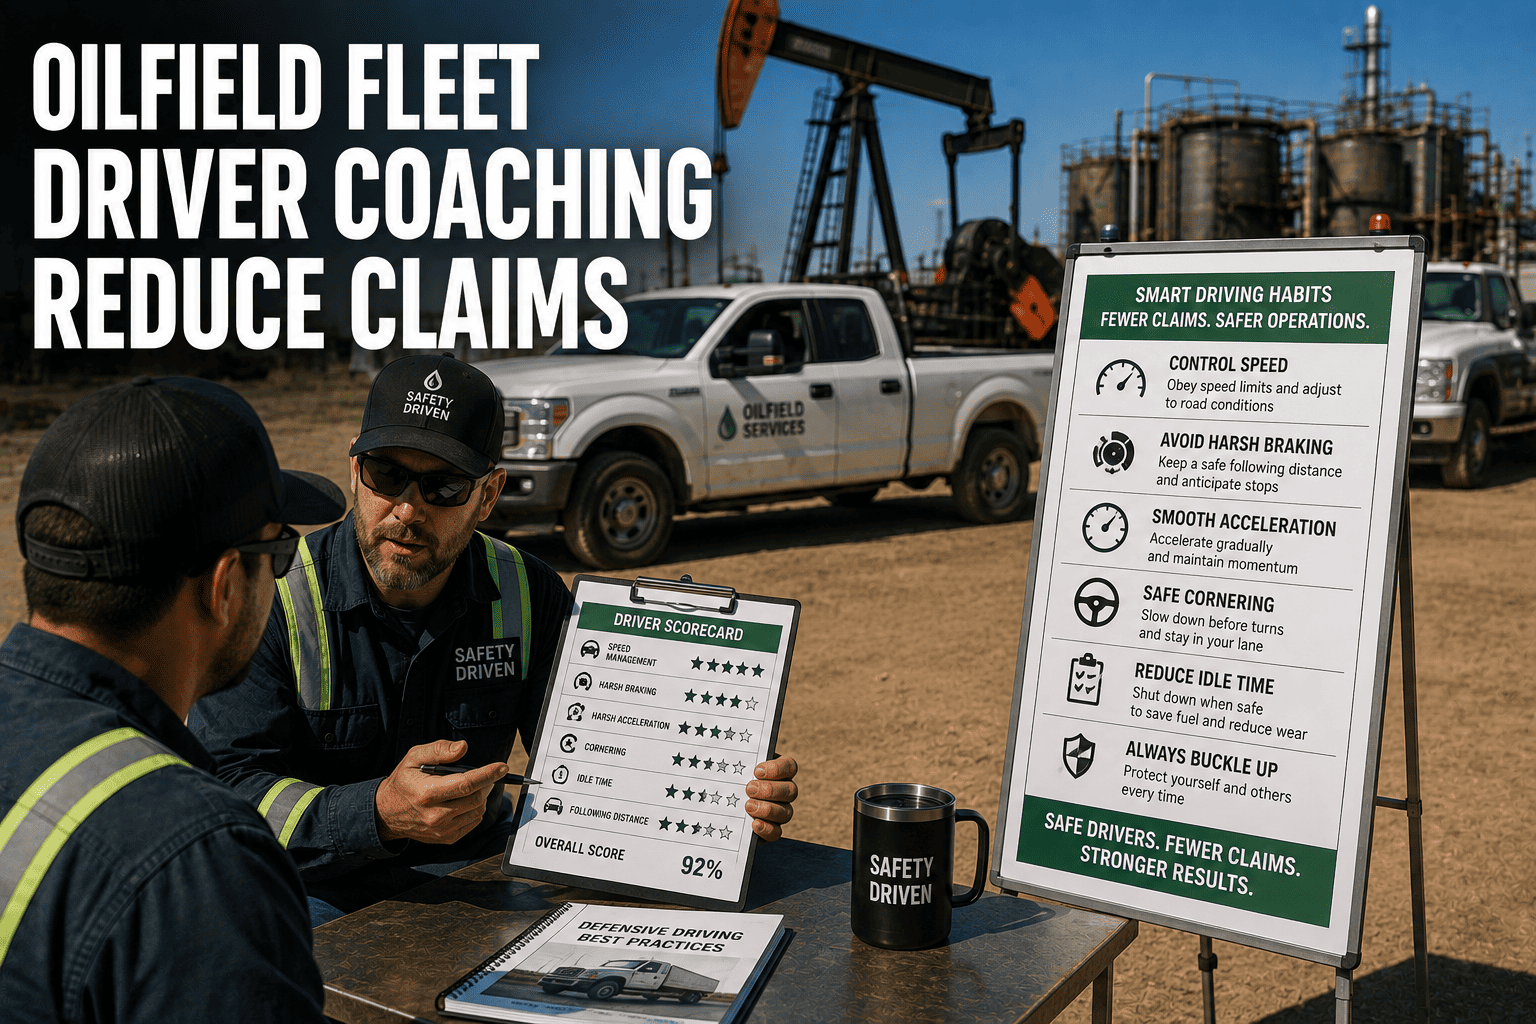
Collecting data earns almost nothing on its own. The fleets seeing the biggest discounts are correcting flagged behavior within days and documenting that the correction happened, turning raw events into a visible downward trend.
Step Three: Package the Evidence for the Broker
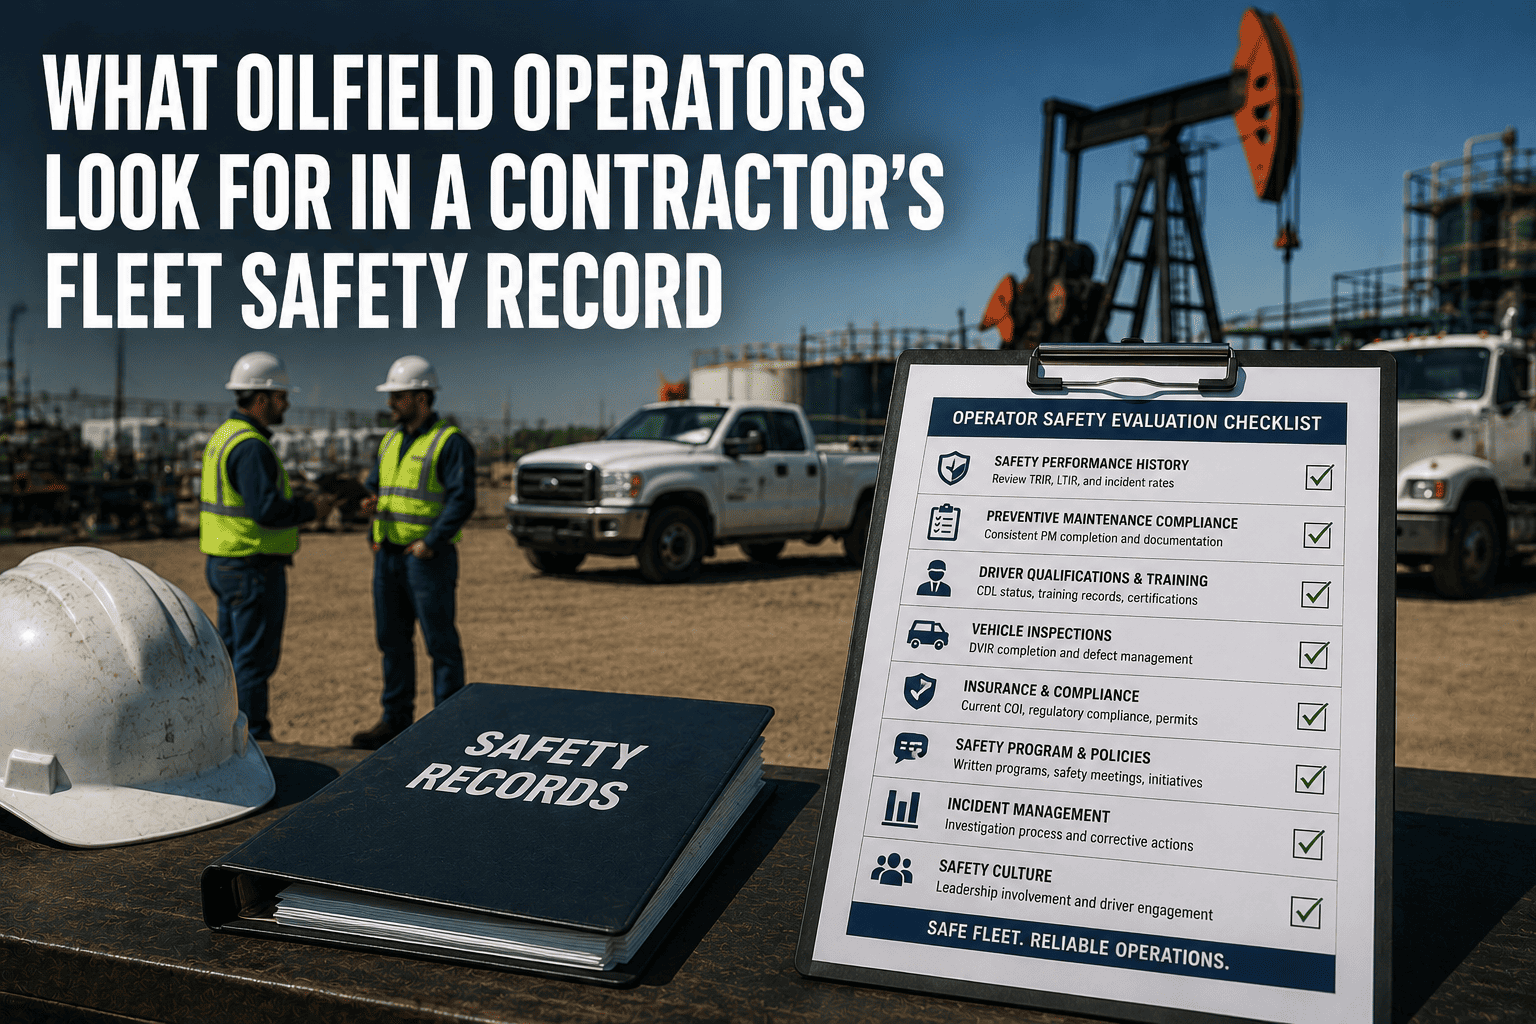
A summarized safety report, not a raw data export, is what lets a broker walk into underwriting with a narrative instead of a spreadsheet the underwriter has to interpret themselves.
Whether your renewal is next month or next year, the sooner your data starts trending in the right direction, the stronger the case your broker walks in with.
Frequently Asked Questions
Your fleet's actual safety performance should set your premium, not an industry benchmark. Sign up to start centralizing the data, or book a demo and we'll show you what a renewal-ready report looks like for your fleet.