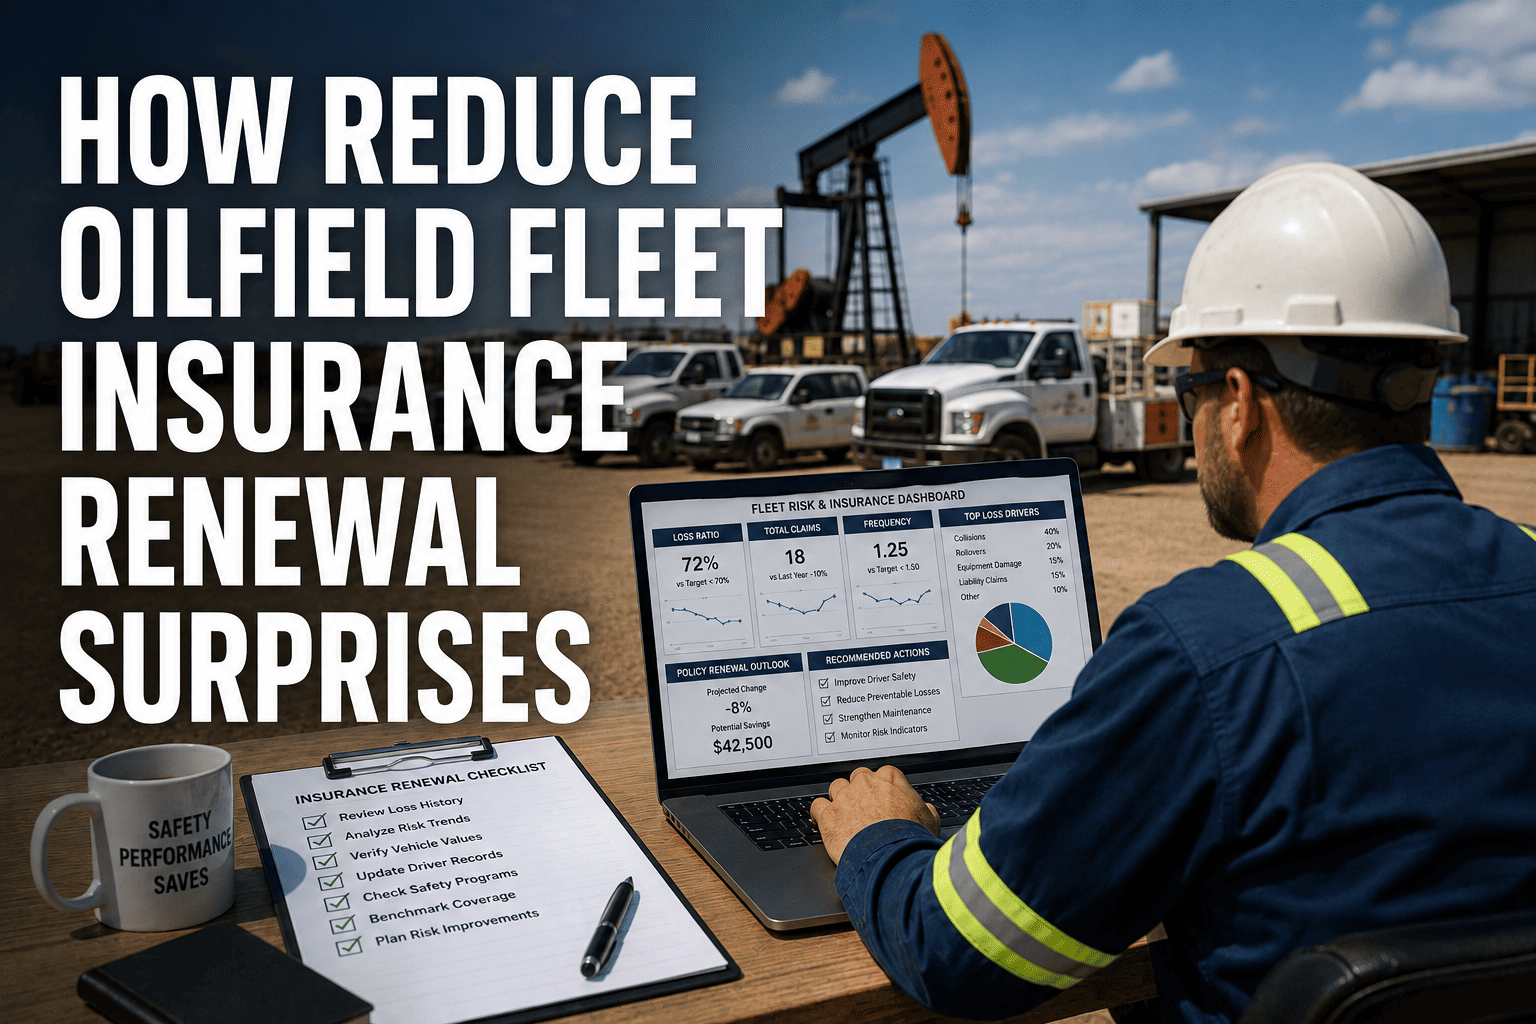
Every oilfield fleet manager knows the sting of a renewal letter that arrives with a bigger number than last year, and usually with no real explanation attached. Insurance underwriters do not price your policy on how safe you believe your operation is. They price it on claims frequency: how often incidents happen, how severe they are, and whether you can prove the pattern is improving. On lease roads, in yards, and across long hauls between pads, that frequency is shaped by things you can actually control, from harsh braking habits to how fast a maintenance issue gets caught. The good news is that claims frequency is not a fixed cost of doing business in oil and gas. It moves, often quickly, once a fleet starts capturing the right data and acting on it.
Oilfield fleets that combine driver behavior monitoring, digital inspections, and fast coaching cycles typically cut recordable incident frequency by 68 to 85 percent and unlock insurance premium reductions of 12 to 24 percent at renewal. A 100-vehicle operation can realistically avoid 280,000 to 580,000 dollars a year in accident-related costs once that trend is documented and shared with underwriters.
Why Claims Frequency Quietly Runs Your Insurance Bill
Claims frequency, not a single bad accident, is what underwriters actually model against. One serious collision gets attention, but it is the steady drip of smaller recordable incidents, harsh-braking events, and near-misses that builds the risk profile insurers price against every single renewal. Oilfield operations carry extra exposure here because of remote lease roads, tight rig-to-rig schedules, and the sheer number of hours drivers spend on unfamiliar or unpaved routes. A single preventable incident can cost 45,000 to 180,000 dollars in direct repair and medical expense, and severe injury claims can push liability exposure past 280,000 dollars. If your fleet cannot show underwriters a documented downward trend, you are almost certainly leaving premium savings on the table at every renewal cycle.
The Real Cost of an Unmanaged Claims Pattern
An adverse claims history does not just raise this year's premium, it compounds. Fleets with a rough loss run often see 18 to 35 percent increases at the next renewal, and that increase follows the fleet for two to three policy cycles even after safety improves, because the loss-run data lags 12 to 24 months behind actual performance. That lag is exactly why fleet managers who want lower premiums cannot wait until renewal season to start proving safety gains. You can start building that record today by choosing to sign up for a free trial and letting the data accumulate before your next policy conversation.
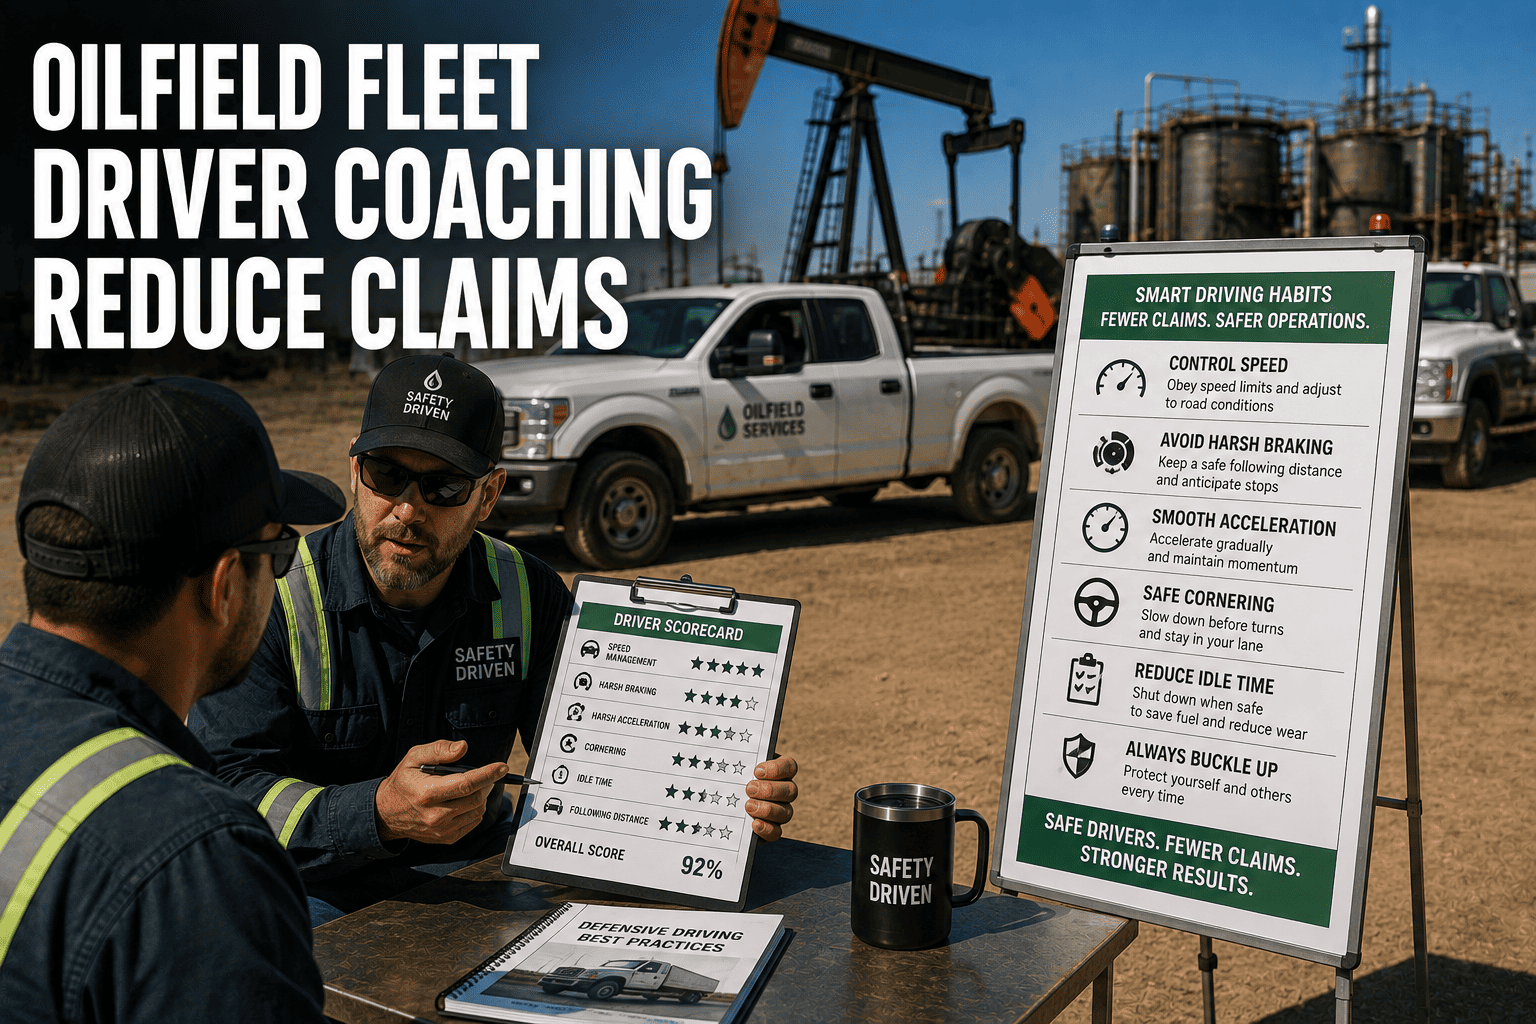
FleetRabbit scores every driver on the events that actually move claims frequency, harsh braking, speeding by zone, HOS compliance, and DVIR completion, then packages the trend into a report your insurance agent can use. Try it free with your own fleet before renewal season starts.
What's Actually Driving Claims Frequency Up On The Lease Road
Underwriters do not see your yard or your drivers. They see numbers on a loss run. Those numbers get shaped by a small set of recurring risk factors that show up again and again in oilfield fleet operations. Knowing which ones apply to your fleet is the first step toward bringing the frequency down.
| Risk Factor | Why It Raises Claims Frequency | What Reduces It |
|---|---|---|
| Harsh Braking Patterns | Frequent hard braking signals tailgating and route unfamiliarity, both statistically linked to rear-end and lease-road collisions | In-cab alerts plus event-level coaching within days of the incident |
| HOS And Fatigue Violations | Fatigue does not just raise frequency, it raises the severity of the claims that do occur | Automated HOS tracking with approaching-limit alerts before a violation happens |
| Deferred Brake And Tire Maintenance | A developing mechanical fault on a remote basin route can turn a routine repair into an emergency breakdown or collision | Digital DVIR with defect escalation instead of paper checklists |
| Speeding By Zone | Unposted lease roads and shifting speed zones near active pads create inconsistent driver judgment | Geofenced speed thresholds tied to real-time driver scorecards |
| Undocumented Safety Culture | Verbal assurances of a strong safety program carry no weight with underwriters without verified data behind them | Continuous behavioral scoring exported into a renewal-ready evidence package |
Five Moves That Actually Bring Claims Frequency Down
None of these require replacing your fleet or overhauling your operation overnight. They require consistent data capture and a coaching loop that closes within days, not weeks.
Score Every Driver On The Behaviors That Predict Claims
Hard braking, harsh acceleration, cornering, and seatbelt compliance are the exact signals underwriting models weight most heavily. Continuous scoring turns anecdotal safety culture into evidence.
Coach Within Days, Not At The Monthly Meeting
Fleets that correct a flagged behavior within days of the event see driver pushback drop from over 60 percent to under 8 percent within 90 days, and the behavior change actually sticks.
Digitize Inspections And Escalate Defects Automatically
A paper DVIR that gets filed and forgotten does nothing for claims frequency. A digital inspection that automatically escalates a brake defect prevents the breakdown that becomes an incident.
Publish Scores And Recognize Improvement
Monthly scorecard publication paired with recognition programs has moved driver safety engagement from a 34 percent paper baseline to over 91 percent at fleets that adopted it.
Bring Documented Data To Every Renewal Conversation
A behavioral score trend, incident frequency reduction percentage, and corrective action log give your agent something concrete to negotiate with, instead of asking underwriters to take your word for it.
What This Looks Like In A Real Fleet
A 94-vehicle operator in the Eagle Ford basin adopted continuous safety monitoring and, over an 18-month measurement period, documented a 41 percent reduction in harsh driving events through systematic coaching. That improved safety score also opened the door to premium client contracts the fleet had previously been excluded from due to a weak safety record. Claims frequency reduction, in that case, paid off twice: once on the insurance side and once on the revenue side.
What Underwriters Actually Want To See At Renewal
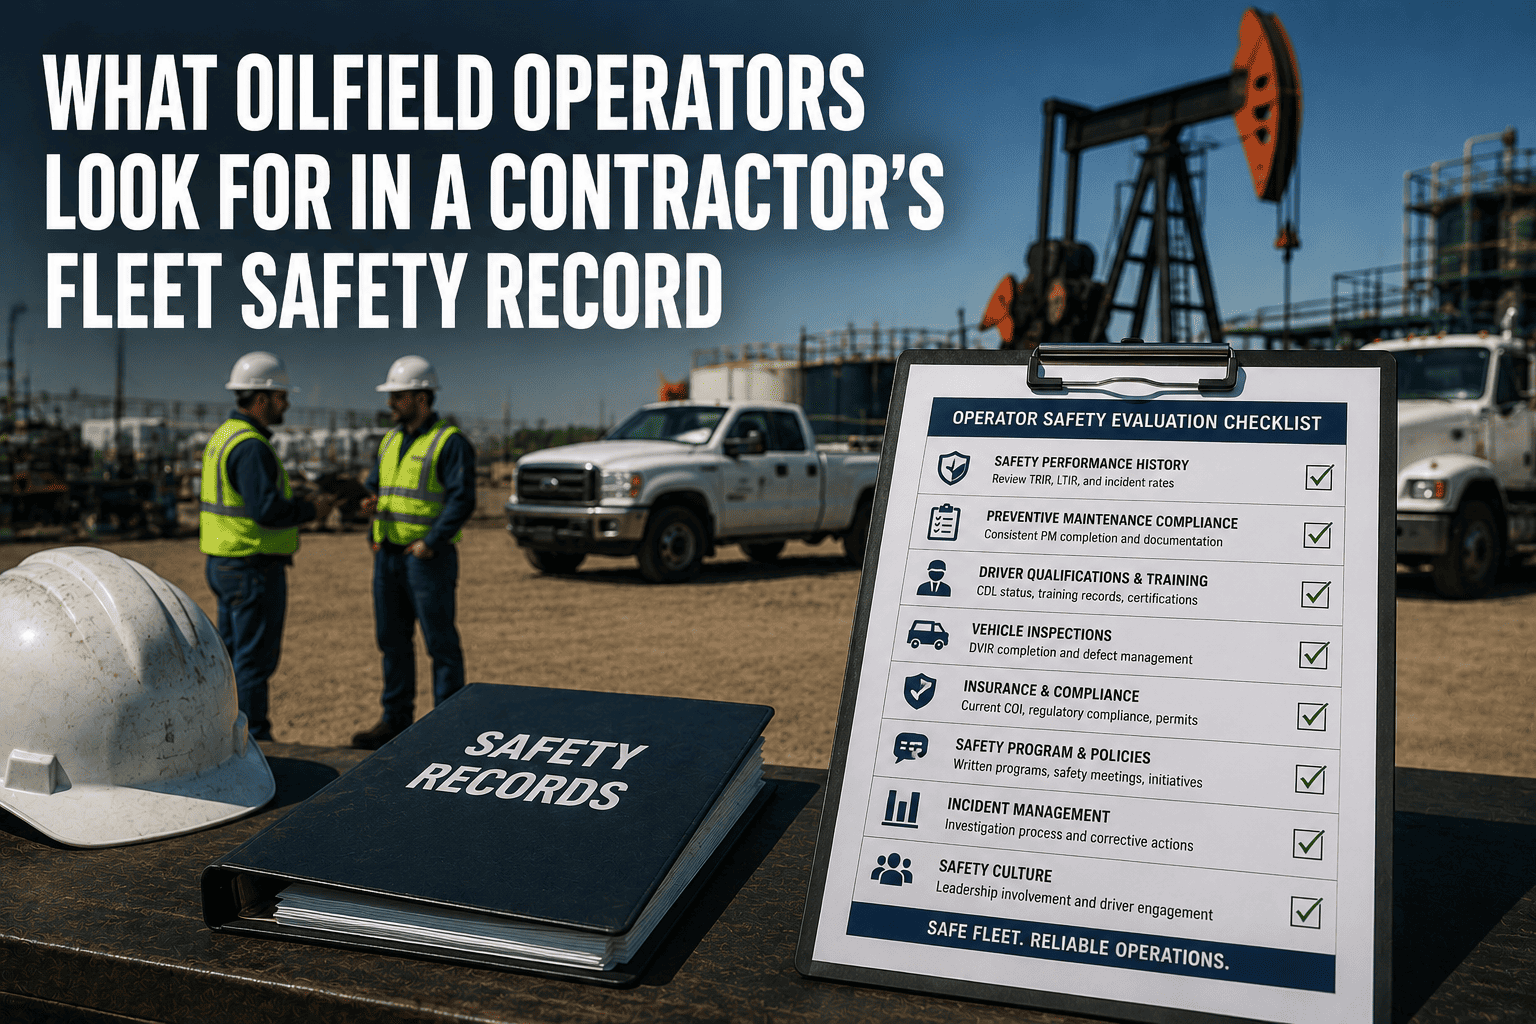
Underwriters do not renegotiate premiums based on good intentions. They respond to a specific evidence package: behavioral score distribution over time, incident frequency reduction expressed as a percentage, digital inspection completion rates, and a corrective action log that shows issues get closed out, not just flagged. Fleets that show up to renewal with this package are the ones capturing the full 12 to 24 percent premium reduction available to them. Fleets that show up with a verbal safety pitch usually get priced at the category average, regardless of how safe their operation actually is.
A Quick Gap Check For Your Fleet
Ask yourself three questions before your next renewal. Can you produce a 12-month trend line for harsh braking events by driver? Can you show a digital, time-stamped DVIR completion rate? Can you point to specific corrective actions closed after a flagged incident? If the answer to any of these is no, that is exactly the gap costing you premium dollars right now, and it is worth exploring how quickly it can close by choosing to book a demo and walking through your current data with a specialist.
How FleetRabbit Builds The Record Underwriters Reward
FleetRabbit's oilfield platform captures the six safety dimensions that carriers actually weigh, hard braking, harsh acceleration, speeding by zone, seatbelt compliance, HOS approaching-limit frequency, and digital DVIR completion, and turns them into a per-driver composite score that updates continuously. GPS-timestamped event records give coaching conversations specifics instead of vague warnings, and monthly scorecards keep the whole fleet engaged instead of just the drivers who get flagged. When renewal season arrives, that same data exports into a report built for your insurance agent, not just your operations team. Fleets deploy in 5 to 7 days at 3 dollars per vehicle per month, with no implementation fee, which means the data trail that lowers your next premium can start building this week.
Frequently Asked Questions
Every month without documented safety data is a month underwriters price your fleet against category averages instead of your actual performance. Start building the behavioral score trend, inspection record, and coaching log that turns your next renewal into a negotiation instead of a bill.