Municipalities, county fleet operations, and public works directors face immense accountability when defending rolling-stock budgets in front of city councils and state oversight boards. The Governmental Accounting Standards Board Statement No. 34 (GASB 34) and the Annual Comprehensive Financial Report (ACFR / CAFR) demand an airtight ledger connecting vehicle acquisition costs, depreciation curves, asset impairments, and actual infrastructure preservation expenses. Operating on disconnected shop work orders or legacy municipal ERP modules forces finance directors into late-night audit reconciliations and leaves fleets vulnerable to sudden budget cuts. FleetRabbit unifies real-time fleet telematics, condition-based depreciation tracking, work order cost accounting, and council-ready capital planning into one intuitive platform. Book a free demo to review our GASB 34 reporting toolkit or explore the live FleetRabbit platform.
Hero Section: Municipal Capital Asset Intelligence HubWhat is GASB 34 Capital Asset Reporting for Public Fleets?
Issued by the Governmental Accounting Standards Board, Statement No. 34 mandates that state and local government entities report all capital assets—including heavy equipment, emergency apparatus, utility trucks, and passenger fleets—on an accrual accounting basis in their Annual Comprehensive Financial Reports (ACFR). Rather than expensing rolling stock when purchased, government agencies must accurately capture initial historical costs, calculate annual depreciation over estimated useful lifespans, and document capital improvements versus ongoing maintenance expenses.
When municipal fleets lack an integrated fleet asset management system, finance departments default to arbitrary depreciation models. This disconnect causes public works departments to either replace assets prematurely or operate aging vehicles past their critical economic repair threshold, inflating taxpayer-funded repair costs.
4 Core Pillars of GASB 34 Fleet ManagementAccurate Historical Cost & Depreciable Basis
Automatically records full acquisition expenses, upfitting costs, auxiliary lighting, and outfitting packages into a defensible capital asset baseline.
Modified Approach vs. Straight-Line Depreciation
Flexibility to choose between standard straight-line asset depreciation or the GASB 34 modified approach by documenting consistent condition assessments.
Capitalization vs. Maintenance Segregation
Delineates whether high-dollar engine or transmission work constitutes a capital asset extension or a routine operating expense.
Council-Ready Disposal & Replacement Plans
Generates multi-year vehicle replacement schedules that link residual asset values directly with projected municipal capital improvement plans (CIP).
Manual Spreadsheets vs. FleetRabbit Automated Capital Asset Reporting
Public fleet managers routinely face skepticism during annual budget hearings. Proving that an ambulance or snowplow has reached the end of its useful life requires more than anecdotal mechanic notes. The comparison below illustrates how FleetRabbit transforms compliance overhead into strategic budget justification.
| Capital Reporting Function | Manual Sheets & Legacy ERP | FleetRabbit Cloud Platform | Municipal Budget Impact |
|---|---|---|---|
| Asset Capitalization | Manual entry; upfits often detached from base VIN | ✓ Automated bundle capitalization | 100% accurate capital asset register |
| Depreciation Tracking | Static calendar years, regardless of idle or hard usage | ✓ Telematics & usage-adjusted depreciation | Prevents premature asset retirement |
| GASB 34 Condition Assessment | Subjective paper inspection logs | ✓ Standardized mobile digital ratings | Enables defensible modified approach |
| Maintenance Cost Attribution | Siloed work orders detached from asset balance sheets | ✓ Real-time cost-per-vehicle ledger | Pinpoints exact economic repair tipping point |
| Audit Retrieval Time | 3 to 5 business days across departments | ✓ Instant 1-click ACFR export | Reduces audit defense overhead by 90% |
ROI Analysis: How Capital Asset Intelligence Defends Municipal Budgets
Public fleet savings are not theoretical. By maintaining strict condition documentation and integrating work order maintenance histories with capital asset valuations, public entities routinely unlock substantial capital savings across their vehicle lifecycle.
Municipal Budget Allocation Optimization
Quantifiable Public Fleet Returns
Under GASB 34, failure to document capital asset condition ratings forfeits an agency's right to use the cost-saving modified approach, forcing default straight-line depreciation. FleetRabbit bridges public works maintenance operations and municipal treasury teams, establishing continuous digital compliance without adding clerical burden to maintenance shop technicians.
Strategic Fleet Replacement: The Economic Tipping Point
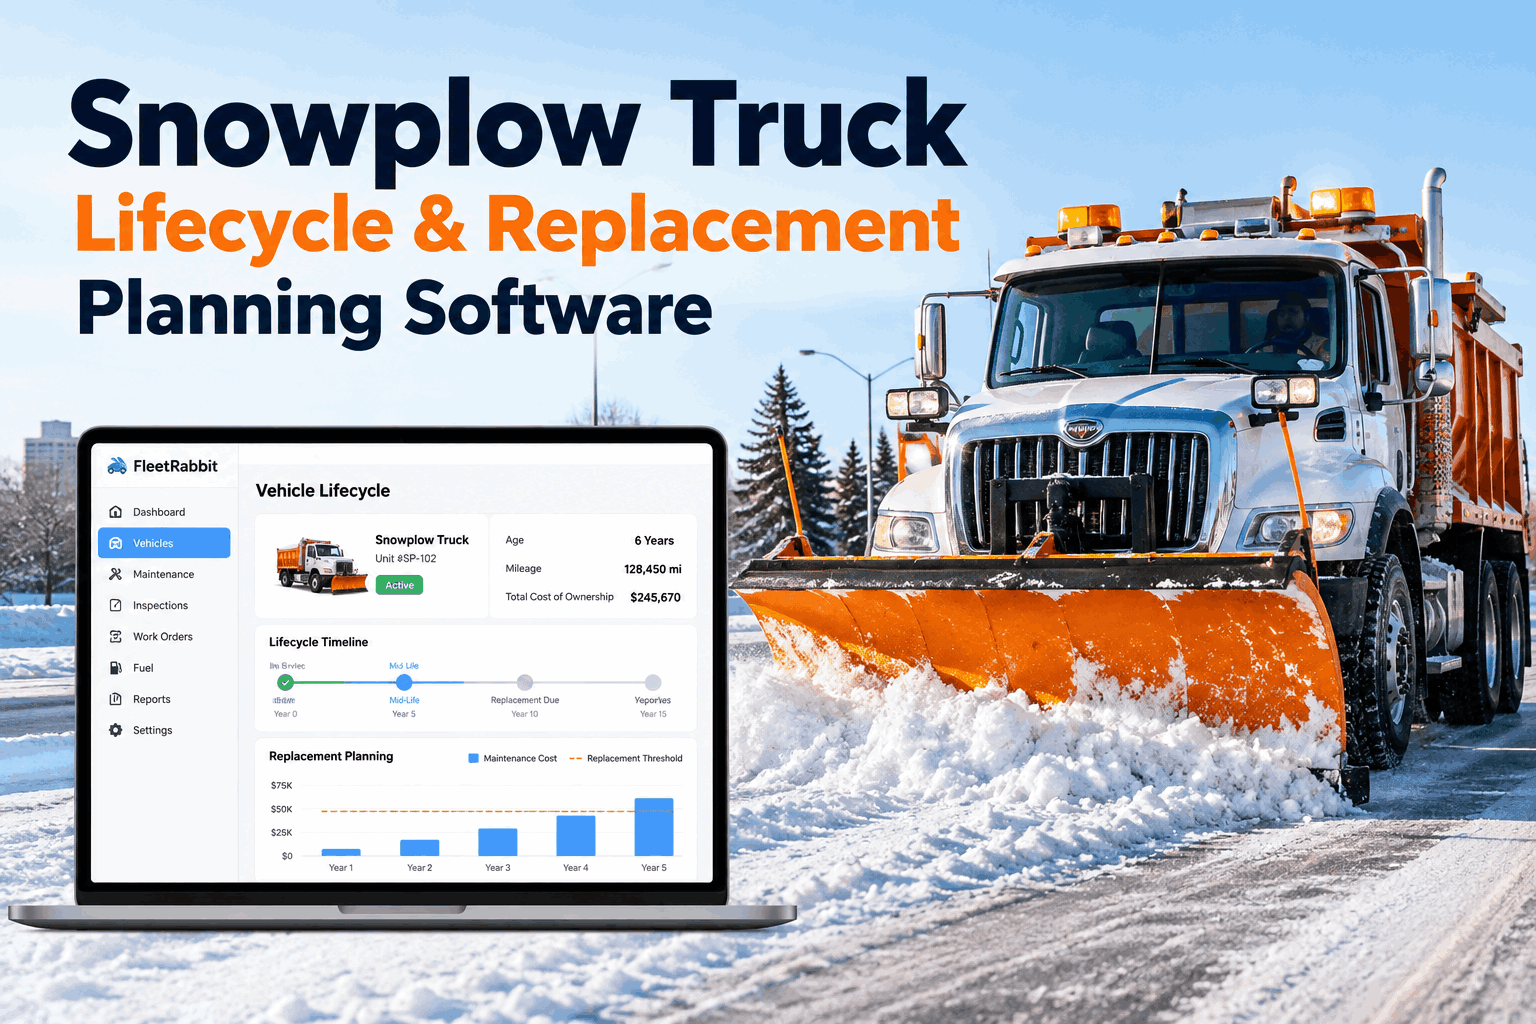
Every municipal vehicle follows an inverted cost curve: as annual capital depreciation decreases over time, cumulative operating and maintenance costs steadily rise. Replacing a vehicle too early squanders invested capital; replacing it too late wastes thousands in emergency repairs, towing, and service disruptions.
High capital value, minimal operating cost. FleetRabbit captures telematics, scheduled servicing, and initial depreciation schedules.
Mid-life overhaul evaluation. FleetRabbit isolates capitalized rebuilds from operating repairs to maintain GASB 34 asset accuracy.
Cost per mile reaches the replacement threshold. FleetRabbit flags the asset for inclusion in the upcoming Capital Improvement Program (CIP).
Automated disposal ledger recording salvage recovery against remaining book value, closing the financial loop for municipal auditors.
Frequently Asked Questions
How does FleetRabbit distinguish between maintenance expenses and capital improvements?
FleetRabbit allows fleet managers and city finance leads to configure specific dollar and scope thresholds. Routine preventive maintenance like fluid changes and brake servicing automatically route to operational expense (OpEx) accounts, while major component replacements (such as full engine or transmission rebuilds) can be tagged as asset extensions to adjust the depreciable capital base.
Can FleetRabbit support the GASB 34 modified approach?
Yes. The modified approach requires regular condition assessments demonstrating that infrastructure or capital assets are being preserved at or above an established benchmark. FleetRabbit’s digital inspection and condition-scoring modules document asset health systematically, providing full audit backing to forgo standard depreciation calculations.
Does this software integrate with municipal ERP systems like Tyler Munis or SAP?
FleetRabbit provides open, robust API connectors and scheduled CSV/financial data export capabilities. This enables automated synchronization of asset values, work order costs, and salvage records directly with municipal general ledgers and public accounting suites.
How does this software assist with city council budget presentations?
FleetRabbit compiles raw fleet telemetry, service records, and capital depreciation curves into visual, executive-ready PDF and slide exports. Fleet managers can clearly demonstrate to city councils why specific vehicles require replacement, supported by hard cost-per-mile and downtime data.
Transform Your Fleet Into a Council-Ready Financial Asset
Take command of your capital replacement schedule, streamline your ACFR audit reports, and reduce municipal fleet overhead with FleetRabbit.