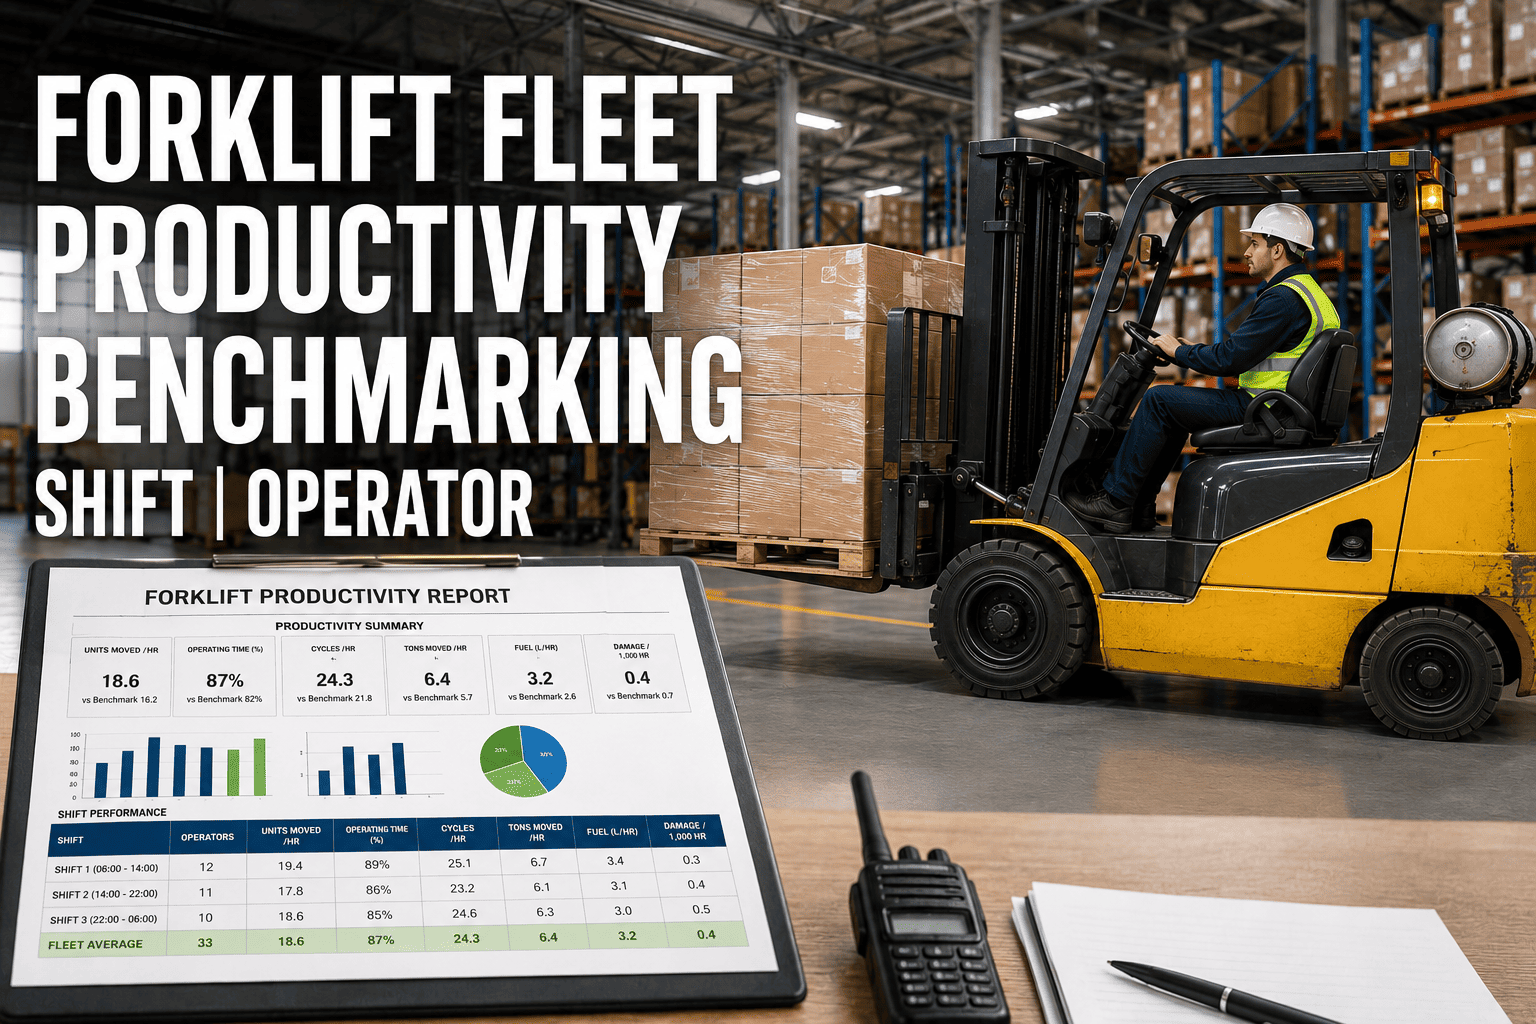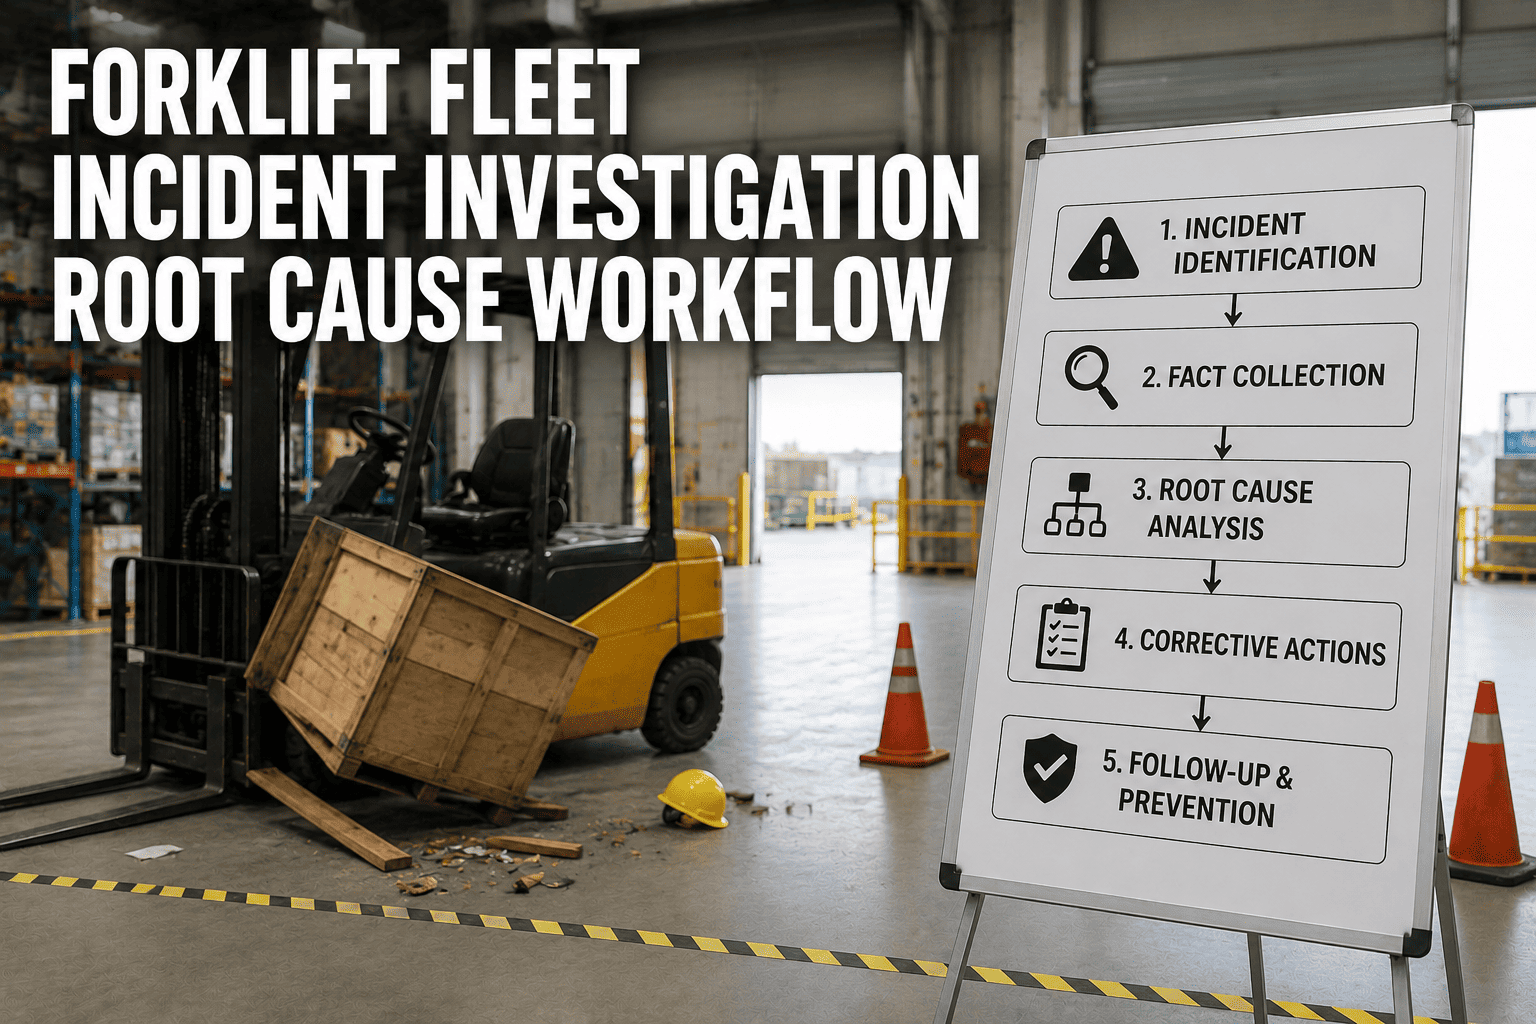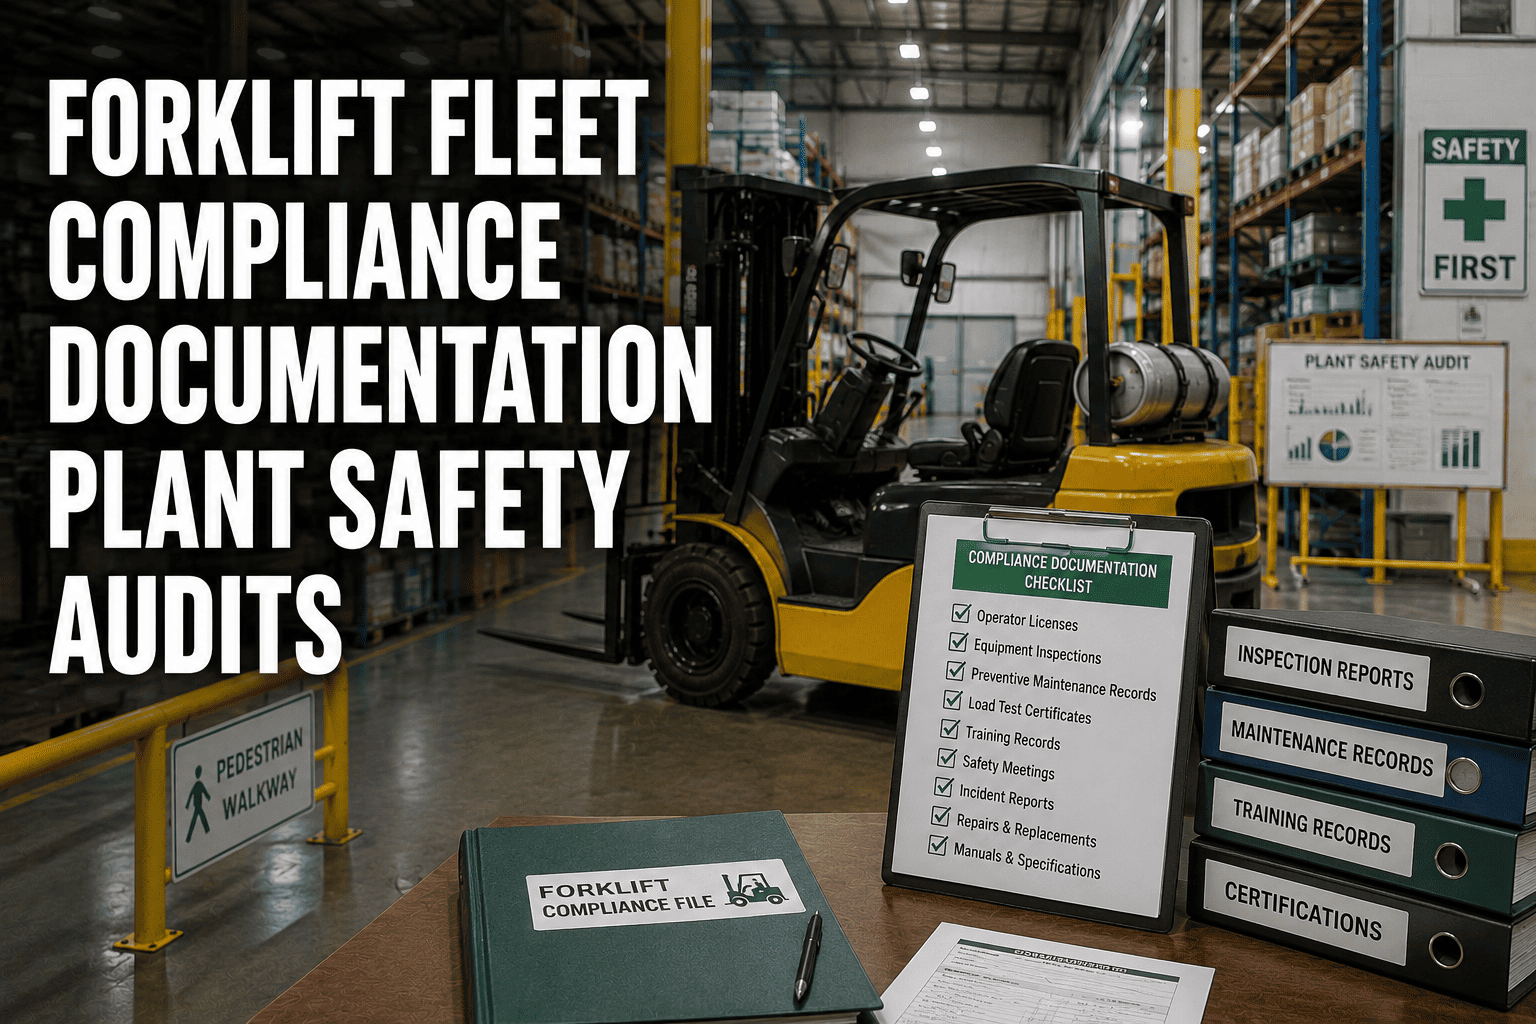
Most plant managers think about forklift safety in terms of injuries and OSHA citations. Insurance underwriters think about it differently: every incident, no matter how minor, becomes a data point that shapes what your plant pays for coverage for years afterward. A single serious claim does not just cost you once. It raises your experience modification rate, follows you through renewal after renewal, and quietly adds tens of thousands of dollars to premiums long after the injury itself has healed. Reducing how often incidents happen on the floor is not just a safety goal anymore, it is one of the most direct ways to control what your plant spends on insurance every single year.
A single forklift workers' compensation claim averages 38,000 to 41,000 dollars in direct costs alone, and indirect costs from lost productivity, replacement labor, and legal exposure typically run four to six times higher, pushing total impact past 200,000 dollars per serious incident. That claim then raises your experience modification rate, increasing what you pay in premiums for multiple renewal cycles afterward. Plants that actively reduce incident frequency see the benefit compound: fewer claims filed, a lower modification rate, and materially lower premiums year over year.
How One Incident Becomes Years of Higher Premiums
The connection between a forklift incident and your insurance bill is not always visible to the safety team, but it is very real to underwriters. Understanding the path from incident to premium is the first step in seeing why claims frequency, not just claim severity, is what insurers actually price against.
An Incident Occurs on the Floor
A collision, a tip-over, or a struck pedestrian happens, often the result of a pattern of risky driving behavior that had been building for weeks without anyone noticing.A Workers' Compensation Claim Is Filed
Medical treatment, lost workdays, and investigation costs begin accumulating immediately, with the average claim reaching tens of thousands of dollars before indirect costs are even counted.Your Experience Modification Rate Rises
Insurers use claims history to calculate a modifier applied to your base premium. More frequent claims push that modifier up, regardless of how severe any single incident was.Premiums Increase at Renewal
A higher modification rate means a higher premium, often for multiple renewal cycles, since underwriters look back several years of claims history when pricing coverage.Coverage Options Narrow
Facilities with a pattern of frequent claims can find it harder to secure affordable coverage at all, as some insurers flag repeat-claim accounts for higher scrutiny or non-renewal.FleetRabbit tracks impact events, harsh braking, and speeding by operator and vehicle, so your team can intervene before a pattern turns into an incident. Sign up to see your fleet's risk data, or book a demo for a full walkthrough.
What Claims Frequency Really Costs Your Plant
The sticker price of a single claim rarely tells the full story. Direct medical and compensation costs are only the starting point once lost productivity, temporary staffing, and legal exposure are added in.
| Cost Category | Typical Impact | Why It Compounds |
|---|---|---|
| Direct Workers' Comp Claim | 38,000 to 41,000 dollars per claim | Median time away from work runs close to three weeks per serious injury |
| Indirect Operational Costs | 4 to 6 times the direct claim amount | Replacement labor, investigation time, and equipment repair stack on top of the claim itself |
| OSHA Citation Exposure | 13,500 to over 160,000 dollars per violation | Incidents often surface training or inspection gaps that trigger separate citations |
| Premium Impact From EMR | Tens of thousands of dollars annually, for multiple years | A single serious claim can affect your modification rate across several renewal cycles |
| Total Incident Impact | 200,000 dollars or more for a serious accident | All categories combine, often far exceeding what shows up on the initial claim report |
The Experience Modification Rate, Explained Simply
Your experience modification rate, often shortened to EMR or e-mod, compares your plant's actual claims history against what is typical for similar operations. An EMR of 1.0 is considered average. Every claim you file pushes that number up, and every claim-free year works to bring it back down. Because insurers look back across a rolling multi-year window, a single bad year of incidents can keep your premiums elevated well after the immediate costs of that year have been paid.
Why Frequency Matters More Than Severity Alone
Underwriters are not just looking at how bad your worst incident was. They are looking at how often incidents happen at all. A plant with several smaller claims can see its modification rate rise just as much as one with a single serious event, which is exactly why reducing the number of incidents matters as much as reducing their severity.
Where Claims Actually Originate on the Floor
Nearly every forklift claim traces back to a pattern that existed before the incident itself. Recognizing these patterns is what turns insurance cost management into a proactive floor-level effort rather than a paperwork exercise after the fact.
Repeated near-misses that go unreported. Small impacts and close calls that never make it into a report are often the clearest early signal that a claim is coming.
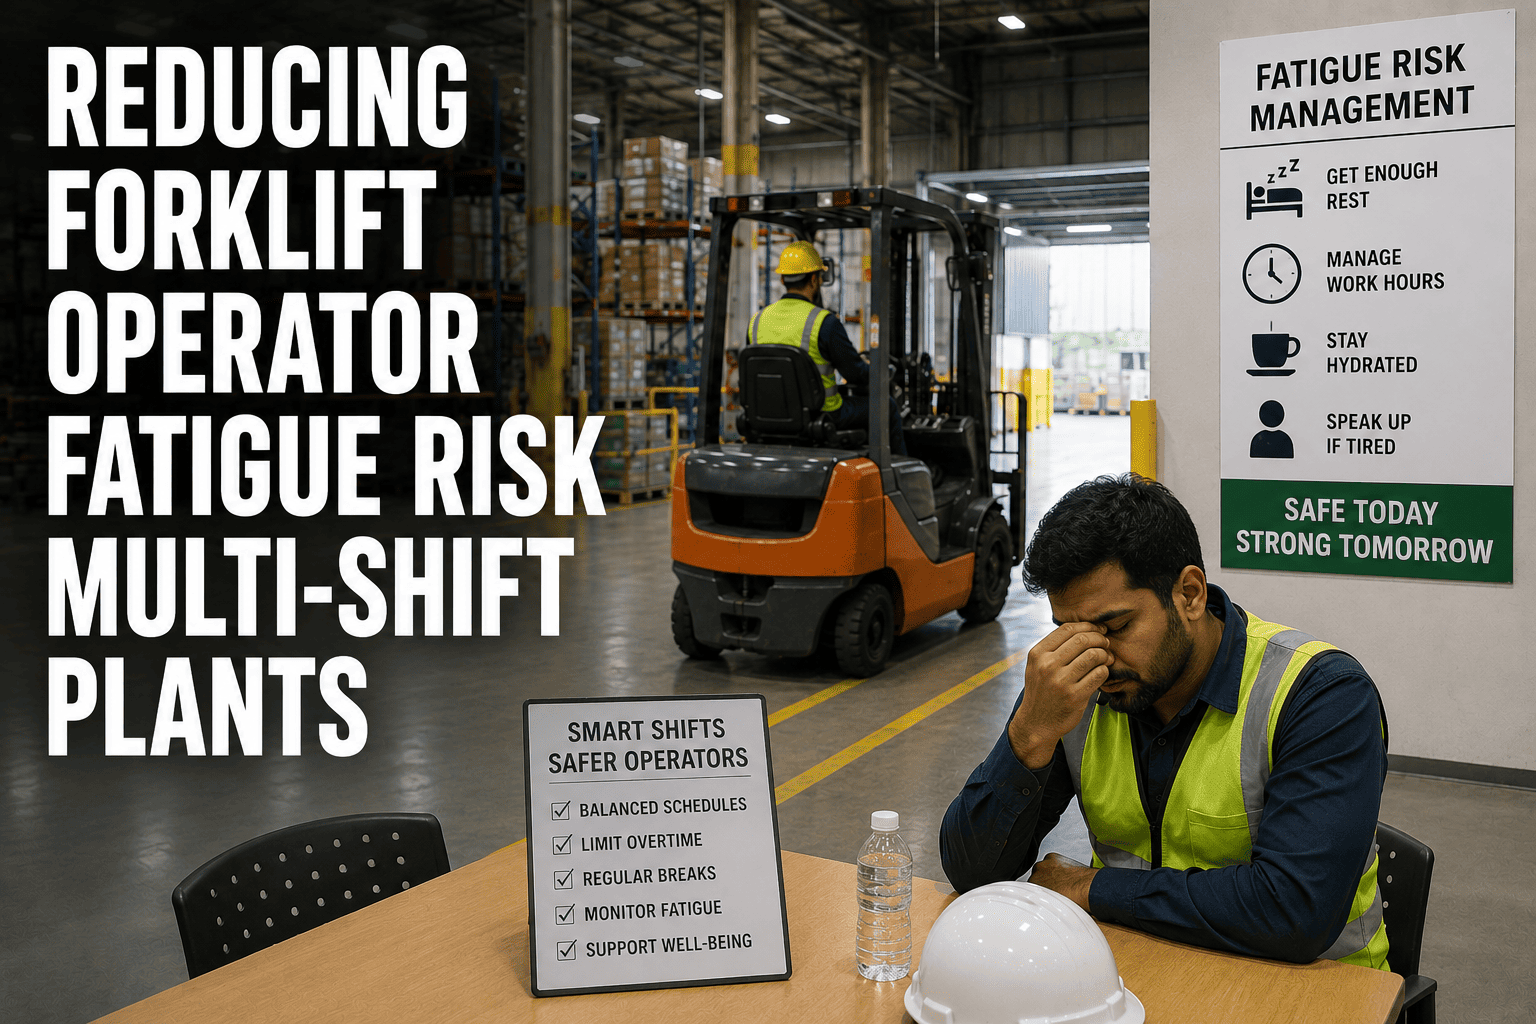
Fatigue on extended shifts. Research shows workers on twelve-hour shifts face notably higher injury risk than those on standard shifts, making shift length itself a claims-frequency factor.
Pedestrian and blind-corner interactions. A large share of the most severe and costly claims involve a forklift striking a pedestrian, often at intersections or blind corners with limited visibility.
New or undertrained operators. Operators without sufficient hands-on coaching are statistically more likely to be involved in the kind of incident that becomes a claim.
FleetRabbit surfaces the near-misses, fatigue risk, and high-traffic pinch points that typically turn into claims, giving your safety team a head start on every one of them. Sign up free today, or book a demo to walk through your own floor data.
How Safety Data Reduces Claims Frequency Before They Happen
Reducing claims frequency is not about reacting faster after an incident, it is about seeing the pattern early enough that the incident never happens at all. FleetRabbit tracks impact events, harsh braking, speeding, and operator behavior across every forklift on the floor, turning scattered warning signs into a clear, ranked view of where risk is building.
When a specific operator or zone starts trending toward risky behavior, safety teams see it in near real time instead of discovering it after a claim is filed. That earlier visibility is what shifts a plant from reacting to claims to actively preventing the incidents that create them, which is exactly the shift underwriters reward with better renewal terms over time.
What Changes for Safety and Risk Teams
Coaching conversations happen before an incident instead of after one, documentation of proactive safety measures becomes part of the record insurers see at renewal, and the plant builds a claims-free track record that steadily works its modification rate back down.
Frequently Asked Questions
Fewer Incidents Is the Real Insurance Strategy
Insurance brokers can negotiate terms, but they cannot negotiate away a claims history that keeps growing. The only lever that reliably brings premiums down over time is reducing how often incidents happen on the floor in the first place, and that starts with seeing the risky patterns that lead to claims long before they turn into one. Plants that build that visibility into their daily operations are not just running a safer floor, they are running a measurably cheaper one to insure.
FleetRabbit gives your safety team the real-time visibility to catch risky forklift behavior before it becomes a claim, building the kind of track record insurers reward at every renewal. Get started with no credit card required.